

As of July 23, 2026, Brent crude has surged toward and above the $100 per barrel level (trading near $99–$100 after settling at $94.07 on July 22), driven by renewed escalations in the Middle East conflict involving Iran, Houthi threats, and disruptions to key shipping routes. As I am writing this, WTI is $91.98, and Brent is $100.07.
Simultaneously, U.S. refineries are operating at near-maximum capacity of 96.1% (week ending July 17), processing about 17.1 million barrels per day (bpd).
This combination signals tight physical markets, elevated refining margins (especially for diesel), and rising costs that will pressure consumers at the pump while creating opportunities—and risks—for energy investors. High utilization reflects refiners capitalizing on strong crack spreads amid global product shortages, but sustained high oil prices risk accelerating demand destruction.
The Four Chokepoints at Play in the Middle East
Global oil trade relies heavily on narrow maritime passages. The primary ones currently under pressure around the Middle East and key transit routes include:
Strait of Hormuz: The world’s most critical oil chokepoint, historically handling ~20–21 million bpd (about 20% of global liquids consumption). Disruptions here have already sharply reduced Persian Gulf flows (down significantly from pre-war levels in recent periods). Alternatives like pipelines (e.g., UAE and Saudi routes) cover only a fraction.
Bab el-Mandeb Strait: The “Gate of Tears” at the southern entrance to the Red Sea (between Yemen and Djibouti). It handles several million bpd (recently elevated as Saudi Arabia diverted exports via Red Sea terminals like Yanbu amid Hormuz issues). Houthi threats and attacks on tankers have raised the risk of a dual-chokepoint crisis, potentially forcing longer routes.
Suez Canal and SUMED Pipeline: Critical for oil moving from the Red Sea/Persian Gulf toward Europe and the U.S. East Coast (~5 million bpd historically). Disruptions at Bab el-Mandeb or related threats cascade here, with alternatives adding substantial voyage time via the Cape of Good Hope.
Related Red Sea/alternative corridor pressures (including impacts cascading toward other routes like those affecting Asian flows via Malacca for downstream product trade): Combined threats amplify longer transport times and higher costs across the system. The Caspian Sea shutdown is in this mix.
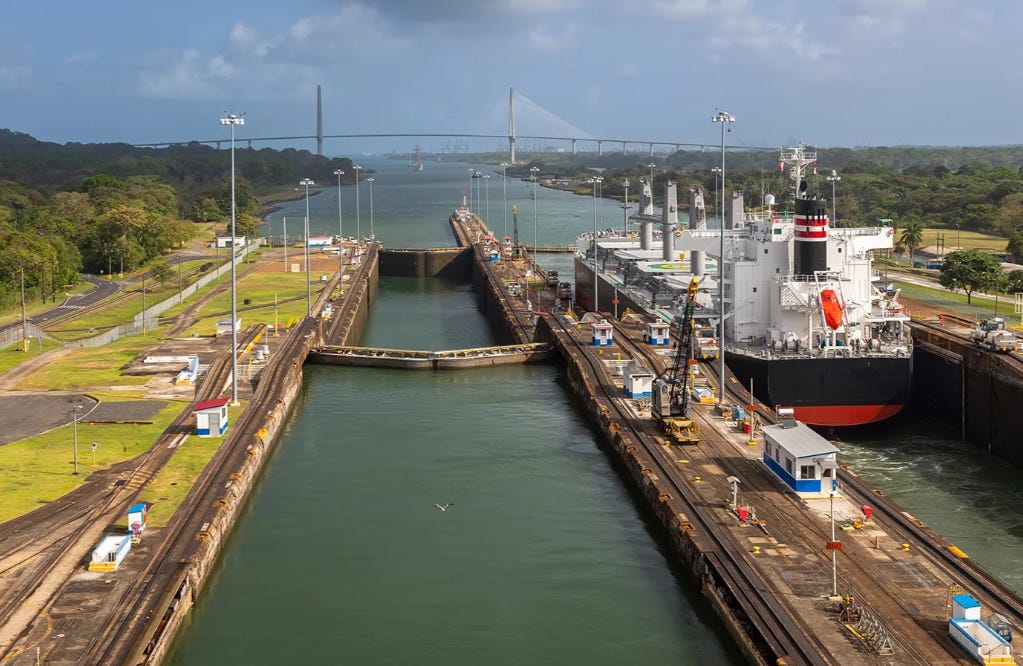
The other one in play is the Panama Canal, which is facing drought issues and may not be able to function at capacity. While this is not a geopolitical issue, it adds weeks to tankers if they cannot use the canal.
These chokepoints are amplifying risk premiums as Houthi actions and broader hostilities threaten Saudi and other exports.
What Oil Analysts Are Saying About Prices
Analysts view the move to $100 as incorporating a renewed risk premium after earlier de-escalation hopes. Goldman Sachs maintains a base-case forecast of ~$80/bbl for Brent in Q4 2026 and $75 in 2027 (assuming de-escalation and recovery in Gulf flows), but stresses upside risks are skewed higher. Prolonged Hormuz disruption could push Brent above $120 by late 2026 and average $100 in 2027.
Other voices, including Brookings’ Robin Brooks, flagged $100 as a near-term target (now reached), with a potential ceiling near the March/April 2026 highs around $125 under severe scenarios (e.g., fuller Hormuz closure). Broader commentary notes that futures still price in relatively temporary disruptions, leaving room for further spikes if infrastructure is hit or dual chokepoints tighten. Inventories are already drawn down, reducing buffers.
EIA Numbers: U.S. Refinery Utilization and Demand
The latest EIA Weekly Petroleum Status Report (week ending July 17, 2026) shows U.S. refineries at 96.1% utilization (down slightly from prior weeks but still elevated), with crude inputs at 17.1 million bpd. Distillate (diesel-heavy) production hit a strong 5.3 million bpd as refiners prioritized high-margin middle distillates. Gasoline output averaged 9.7 million bpd.
Commercial crude inventories rose 2.0 million barrels to 411.7 million (still 6% below the five-year average). Gasoline and distillate stocks remain below average. Four-week average total product demand was 20.4 million bpd (down ~1% year-over-year), with gasoline demand up 1% to 8.9 million bpd, distillate up 2% to 3.7 million bpd, and jet fuel notably higher (+9% YoY). Strong utilization is supporting crude demand even as overall product supplied shows mixed signals.
West Coast (PADD 5) utilization lagged at 88.7%, highlighting regional tightness.
California’s Import Numbers, Prices, and Asia Supply Risks
California remains highly dependent on imports due to prior refinery closures (reducing capacity) and limited local production. The state has imported significant volumes of gasoline and blendstocks from Asia (South Korea, India, and others), with Asia historically supplying a large share—around 20% of gasoline in recent periods—and overall product imports elevated (hundreds of thousands of bpd in peaks).
Los Angeles regular gasoline retail prices recently hovered around $5.32–$5.43/gallon (all grades higher), well above the national average. Spot RBOB in Los Angeles has also been elevated.
Asia is not fully cut off yet, but the region’s refiners face constraints from Middle East crude disruptions. Longer Pacific voyage times (25–45 days) mean lagged impacts. California has flexibility via some domestic/Gulf reroutes and other sources (e.g., Bahamas transit), but further Asia product curtailments or higher costs could tighten supply and push prices higher. The state is vulnerable but not immediately isolated.
When Will Demand Destruction Kick In and Balance Higher Prices?
Demand destruction—the reduction in consumption due to high prices—has already begun. The IEA and others noted significant contractions earlier in 2026 (hundreds of thousands to over a million bpd in peak disruption periods), with forecasts of overall 2026 demand declines before partial recovery. Prices at or above $100/bbl historically trigger more meaningful destruction, particularly in price-sensitive sectors and emerging markets.
Balancing could accelerate in late Q3/Q4 2026 if prices sustain or climb further (forcing efficiency, fuel switching, or reduced driving/travel), especially with already-low inventories. However, summer driving and jet demand provide near-term support. Full balancing depends on the duration of supply disruptions; prolonged tightness may require even higher prices to destroy enough demand.
Paper vs. Physical Prices Amid Higher Tanker Fees and Longer Transport Times
The physical market is tighter than paper (futures) pricing suggests in many cases. Disruptions have forced longer voyages (e.g., via the Cape of Good Hope, adding ~10–14+ days), spiking VLCC and other tanker rates substantially in recent periods (with weekly jumps of 40–90%+ on key routes at peaks). Higher insurance, security premiums, and freight costs inflate the delivered cost of physical barrels.
This has contributed to backwardation (near-term premiums) or physical premiums over futures at times, as buyers pay up for prompt, non-disrupted supply. Paper markets incorporate expectations of eventual de-escalation, while physical reflects immediate logistics realities and low stocks. The disconnect underscores risk for consumers (higher product prices) and potential upside for physical-oriented investors or those positioned for sustained tightness.
Implications for Consumers and Investors
Consumers face higher gasoline and diesel prices (already elevated, especially in California and for distillates nationally), with further upside risk if chokepoints tighten. Demand destruction may eventually cap prices but only after pain. Investors in upstream producers, refiners (benefiting from high utilization and cracks), and tanker operators could see gains from the tight physical market, while those exposed to broader inflation or rate-sensitive assets face headwinds. Monitor Hormuz/Bab el-Mandeb flows, EIA inventories, and tanker rates closely.
What we are seeing:
At Pecos Operating, we are seeing the spike in oil prices as a short-term spike and are not changing our drilling programs. Much like the rest of the Oil and Gas Exploration and Production companies, we are now using much more controlled drilling programs, keeping steady cash flow and returns to investors. Even the Crown Prince of Saudi Arabia has said it is better for the oil and gas markets to have steady prices rather than volatility.
I am prepping for several interviews, and we will have that on our Pecos In The News on our YouTube Channel.
Check out LFS Chemistry, Sponsor of the Crude Truth, here:
Follow Rey on his LinkedIn: https://www.linkedin.com/in/reytrevinoiii/
Also, Pecos Operating Website:
Appendix: Sources and Links
Morningstar/Dow Jones: Front Month ICE Brent Crude Rose 3.36% to Settle at $94.07 (July 22, 2026 data) — https://www.morningstar.com/news/dow-jones/202607227497/front-month-ice-brent-crude-rose-336-to-settle-at-9407-data-talk
FT.com commodities data (Brent near $99, WTI ~$91 as of July 23) — https://markets.ft.markitdigital.com/data/commodities/tearsheet/summary?c=WTI+Crude+Oil
Investing.com Brent historical/futures data — https://jp.investing.com/commodities/brent-oil-historical-data (and related)
EIA Refiner Operable Capacity Percent Utilization — https://www.eia.gov/dnav/pet/PET_PNP_WIUP_A_%28NA%29_YUP_PCT_W.htm
EIA Today in Energy: Commercial crude oil inventories (week ending July 17, 2026) — https://www.eia.gov/todayinenergy/detail.php?id=67868
RBN Energy: Refinery Utilization Holds Above 96% — https://rbnenergy.com/daily-posts/analyst-insight/refinery-utilization-holds-above-96-strong-diesel-margins-drive
Reuters: After Hormuz, Iran turns to Red Sea gateway — https://www.reuters.com/world/middle-east/after-hormuz-iran-turns-red-sea-gateway-new-pressure-point-2026-07-14/
Straits.live: World Shipping Chokepoints comparison — https://straits.live/world-shipping-chokepoints
OilPrice.com historical chokepoints overview — https://oilprice.com/Energy/Energy-General/The-4-Key-Chokepoints-For-Oil.amp.html
Goldman Sachs forecasts coverage (various, e.g., Exchange Rates.org.uk, Oil & Gas Middle East) — https://www.exchangerates.org.uk/news/46596/2026-07-23-goldman-sachs-oil-price-forecast-brent-risks-remain-skewed-to-the-upside.html; https://www.oilandgasmiddleeast.com/news/brent-risks-120-surge
Robin Brooks commentary (via X/Substack references) on $100 target
EIA Los Angeles gasoline/diesel prices — https://eia.gov/dnav/pet/pet_pri_gnd_dcus_y05la_w.htm
EIA Gasoline and Diesel Fuel Update — https://eia.gov/petroleum/gasdiesel
Institute for Energy Research / related on California imports — https://www.instituteforenergyresearch.org/international-issues/refinery-closures-increase-californias-reliance-on-fuel-imports/
Pecos Operating / Kpler-linked California import analysis — https://pecosoperating.com/how-much-diesel-gasoline-jet-fuel-and-other-oil-products-are-actually-imported-to-california/
NYT and IEA-related demand destruction coverage — https://www.nytimes.com/2026/06/07/business/demand-destruction-iran-war.html
Lloyd’s List / Baltic Exchange tanker rate references — https://www.lloydslist.com/LL1157631/VLCC-rates-spike-yet-again-as-confusion-continues-to-reign-at-Strait-of-Hormuz
Additional supporting EIA tables, FT, Bloomberg, CNBC, and analyst reports referenced in real-time market coverage as of July 23, 2026.
Data is current as of available reports around July 22–23, 2026; markets remain highly volatile.