

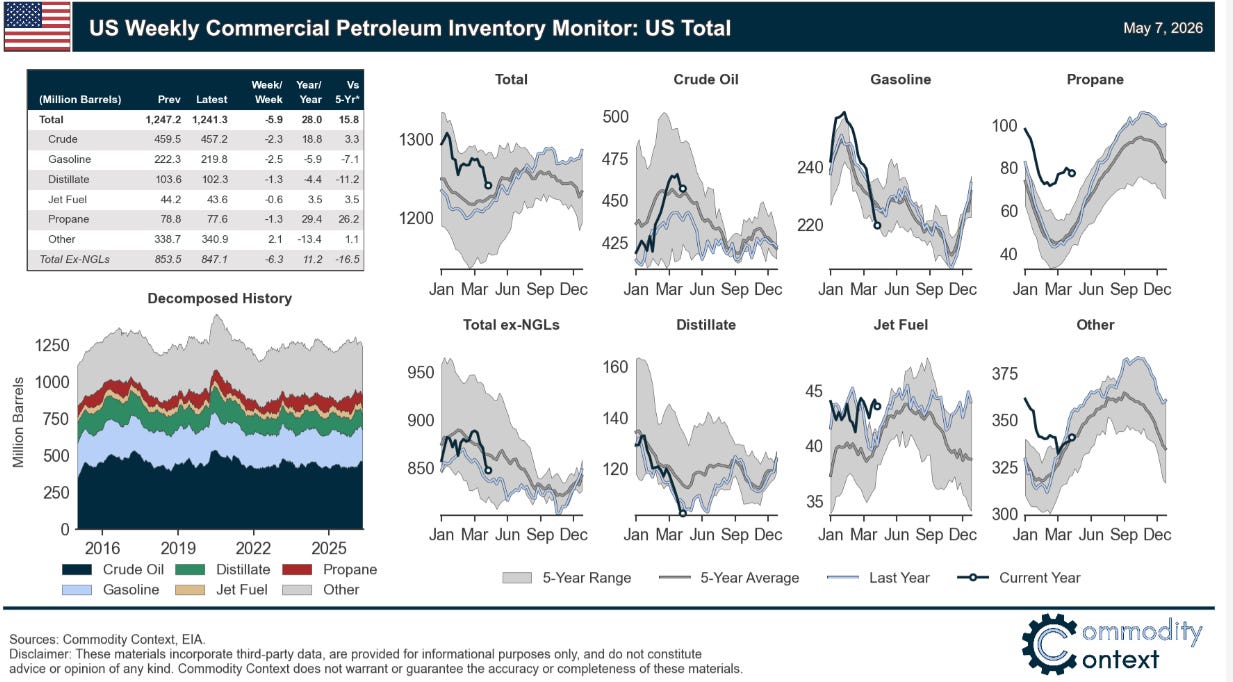
In a notable shift amid persistent global supply tightness and geopolitical volatility, the U.S. Energy Information Administration’s (EIA) Weekly Petroleum Status Report for the week ending July 3, 2026 (released July 8) revealed a rare build in commercial crude oil inventories. U.S. commercial crude stocks (excluding the Strategic Petroleum Reserve) rose by 3.0 million barrels to 411.4 million barrels—still about 6% below the five-year average for this time of year.
This build contrasts with recent weeks of draws and comes as total commercial petroleum inventories fell by 4.0 million barrels overall, driven by product stock draws. The data highlights a complex market: crude supply showed temporary relief, but refined product balances remain under pressure while broader geopolitical risks from the Middle East continue to support prices.
Key EIA Inventory Highlights (Week Ending July 3, 2026)
Commercial Crude Oil: +3.0 million barrels to 411.4 million barrels (~6% below five-year average). This marks a reversal from the prior week’s draw of ~3.8 million barrels (to 408.4 million).
Motor Gasoline: Decreased by ~1.9–2.0 million barrels; levels remain below seasonal averages.
Distillate Fuel Oil (including diesel and heating oil): Decreased by 5.0 million barrels (~12% below five-year average).
Propane/Propylene: Decreased by 0.829 million barrels.
Refinery Activity: Inputs averaged 17.0 million barrels per day at 95.8% utilization. Crude imports rose by 351,000 barrels per day.
Strategic Petroleum Reserve (SPR): Continued significant drawdowns. Recent data show stocks falling by 6.2 million barrels to approximately 319.5 million barrels in the latest reported week—the lowest level since 1983.
Cushing, Oklahoma (key WTI delivery hub) stocks stood at approximately 19.666 million barrels as of the week ending June 26 (a +709,000 barrel build after nine consecutive weeks of declines). Levels remain near multi-year lows and close to operational stress points, reflecting tight conditions at this critical pricing and logistics node.
Jet fuel inventories have generally held above recent averages in prior months amid elevated production and exports responding to global disruptions, though specific weekly changes for the latest period align with broader product tightness trends.
Chart/Trend Context: U.S. commercial crude inventories have trended downward over recent months due to strong refinery demand and SPR releases offsetting global shortfalls. The latest build may reflect higher imports or slightly softer refinery runs in spots, but the overall picture (including products) remains one of below-average stocks. Cushing’s prolonged drawdown-to-lows underscores physical tightness at the futures settlement point. SPR depletion has accelerated amid conflict-related supply gaps.
Source: Commodity Context
Geopolitical Backdrop: Iran, Sanctions, and Hormuz Risks
This inventory snapshot unfolds against escalating Middle East tensions. The Strait of Hormuz—through which roughly 20% of global seaborne oil trade flows—has faced significant restrictions or control by Iran since late February 2026. EIA assessments suggest marine traffic is unlikely to fully return to pre-conflict norms until early 2027, contributing to record OECD inventory drawdowns and expectations of elevated prices.
A U.S.-related MOU (sanctions waiver or relief framework) has ended, with Iran reportedly violating key terms. This triggered the reimposition of sanctions on Iranian oil exports. Approximately 63 million barrels of Iranian crude already loaded onto tankers are now stranded or without clear buyers, threatening Tehran’s revenue streams.
China’s role stands out as a major market signal: reports indicate that Beijing has given refineries (including independent “teapot” refineries in Shandong) the green light to resume or continue purchasing Iranian barrels despite sanctions risks. China remains Iran’s primary customer through shadow-fleet operations, and this stance could sustain discounted flows even as broader enforcement tightens.
Oil prices have responded with upside volatility. As of early July 8 trading, WTI hovered around $75 per barrel (with sharp intraday gains), and Brent near $79–80 per barrel, reflecting geopolitical risk premiums layered onto fundamentally tight balances.
Implications for Investors
The rare crude build offers a short-term data point of relief but does not fundamentally alter the bullish-leaning setup for energy markets:
Price Support: Global inventories (especially in the OECD) are heading toward multi-decade lows due to lost Middle Eastern output and disruptions in the Strait of Hormuz. Combined with low SPR levels and product draws, this creates a floor under prices if risks persist or escalate.
Sector Opportunities: Upstream producers and explorers benefit from higher realized prices. Midstream (pipelines, storage) may see Cushing dynamics play out in basis and spreads. Refiners could enjoy strong crack spreads amid gasoline/distillate tightness. Energy equities and related ETFs may attract flows on sustained geopolitical premiums.
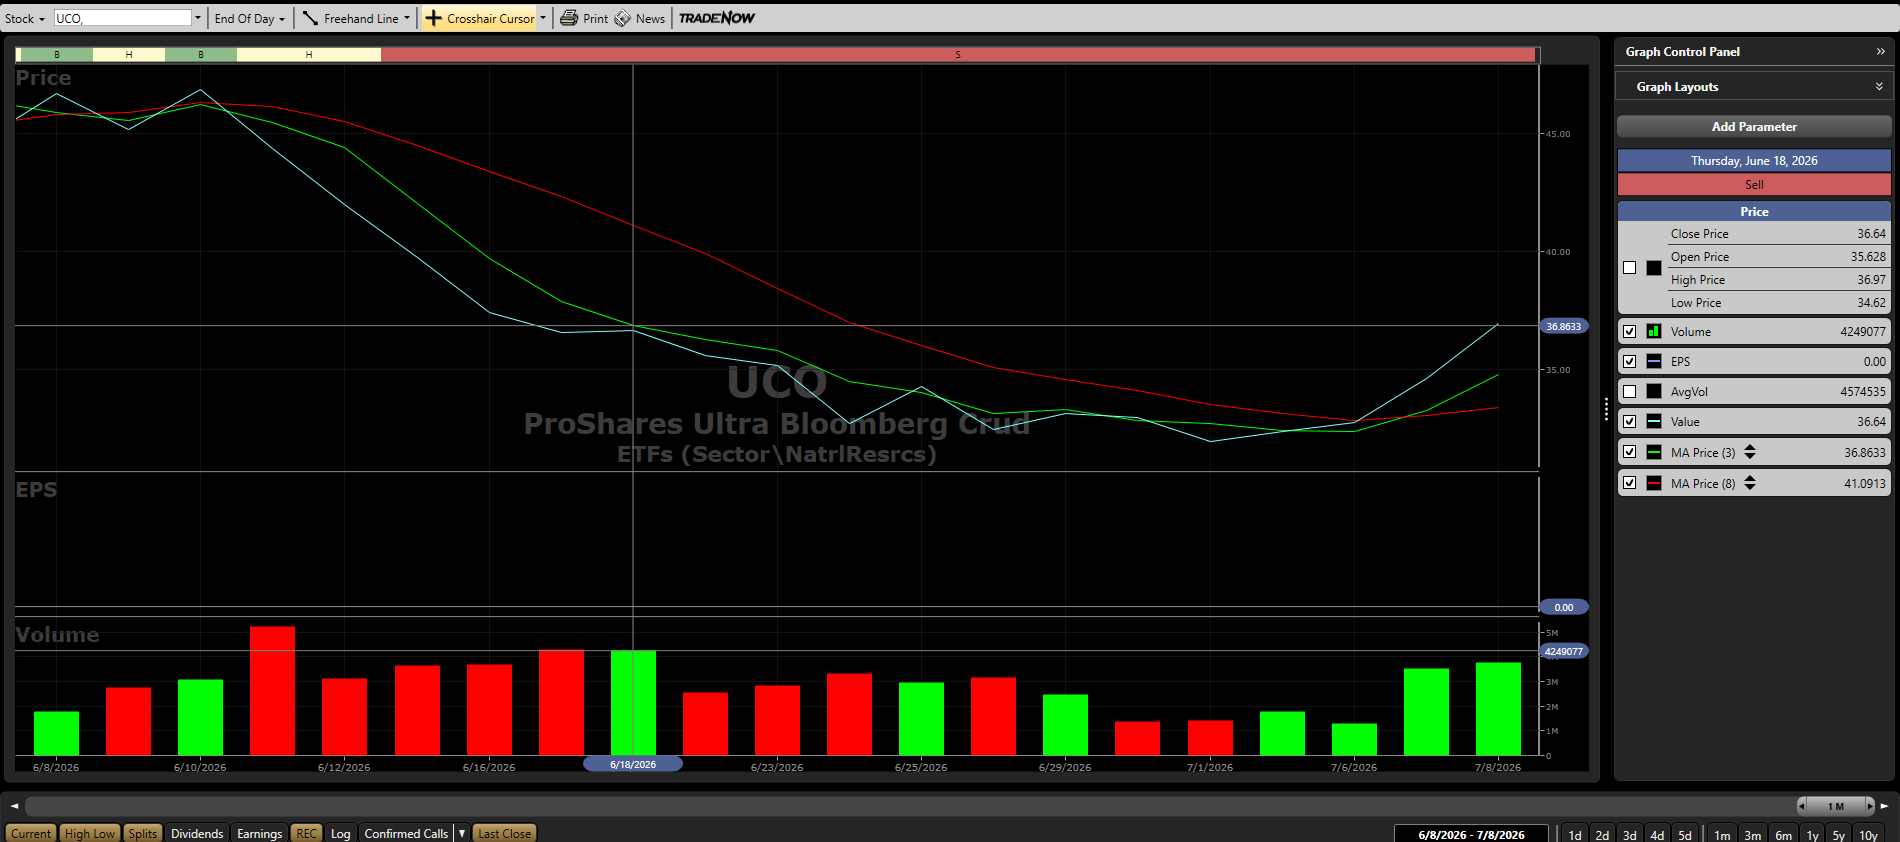
One ETF is Bloomberg’s Crude.
For investors, this is one that has the markings of going up, but it does not have the tax advantages of investing closer to the well.
Source: VectorVest
Risks and Watchpoints: A sudden de-escalation or resolution in Hormuz/Iran tensions could trigger sharp pullbacks. Monitor upcoming EIA reports for follow-through on the build, refinery utilization, and product supplied (demand proxy). The 63 million barrels of sanctioned Iranian oil and China’s buying signals add layers of uncertainty—discounted barrels could ease some pressure if they find homes, but enforcement risks remain.
Overall, the inventory data reinforces a market sensitive to supply shocks rather than signaling abundant slack.
Implications for Consumers
U.S. drivers, truckers, airlines, and households face potential headwinds:
Fuel Prices: Gasoline and diesel at the pump could see upward pressure from tight product inventories, higher crude costs, and any widening of crack spreads. Jet fuel costs for airlines (and ultimately ticket prices) remain sensitive to global supply concerns.
Resilience Factors: Strong U.S. domestic production and remaining (though depleted) SPR provide some buffer. However, low SPR levels limit further emergency releases.
Broader Effects: Prolonged disruptions could contribute to higher transportation and energy costs, feeding into inflation. Summer driving and air travel seasons add seasonal demand support that could amplify price moves.
Longer-term relief depends on the resolution of Hormuz/Iran issues or the successful rerouting of supplies.
Bottom Line
The EIA’s rare crude build is a positive short-term data surprise in an otherwise tightening environment. Yet it sits within a high-stakes geopolitical context: re-sanctioned Iranian oil (including 63 million barrels afloat), China’s market signals to its refineries, and the risk of a prolonged Strait of Hormuz shutdown. These factors continue to underpin oil price strength and market volatility.
Investors should view energy as a sector with asymmetric upside from supply risks, while remaining vigilant on inventory follow-through and diplomatic developments. Consumers may need to prepare for elevated fuel costs in the near term. The energy landscape remains delicately balanced between temporary inventory relief and structural/geopolitical pressures.
We are watching the rebuilding of the oil markets starting in the Gulf Countries. Saudi Arabia, Iraq, Kuwait, and the UAE all have new pipeline projects underway or in discussion. Within 1 to 2 years, the Strait of Hormuz will not have a huge impact on oil or be a revenue stream for Iraq.
For LNG and Europe, it remains a major issue. The US has stepped in to fill the gap, but it is a huge issue, and they are running behind in filling their natural gas reserves for the summer. Qatar, the number 2 global LNG exporter, has notified folks that they will not be supplying shipments through September. That is cutting the winter fill schedule close, and they are not sure they can make October or November shipments as of this morning.
Energy Security is now the single biggest topic worldwide.
What a time to be in the oil and gas space, delivering the lowest cost energy in the world with the least impact on the environment.
We love what we do at Pecos Operating, and it shows. And That Is The Crude Truth.
Follow Rey on his LinkedIn: https://www.linkedin.com/in/reytrevinoiii/
Also, Pecos Operating Website: https://pecosoperating.com/
Appendix: Sources and Links
EIA Weekly Petroleum Status Report (week ending July 3, 2026, released July 8): https://www.eia.gov/petroleum/supply/weekly/ and summary PDF https://ir.eia.gov/wpsr/wpsrsummary.pdf
EIA Cushing, OK Crude Stocks: https://www.eia.gov/dnav/pet/pet_stoc_wstk_dcu_ycuok_w.htm
SPR and related draws: Reuters reporting (e.g., July 2026 articles on lowest levels since 1983)
Geopolitical/Iran/Hormuz context: Reuters EIA Short-Term Energy Outlook coverage; reports on 2026 Strait of Hormuz developments
63 million barrels Iranian oil on tankers: July 2026 reporting (e.g., UNN.ua/Bloomberg/Vortexa-based coverage)
China/refinery signals and sanctions: Industry and news reports on teapot refineries and shadow fleet activity
Oil prices: Trading Economics, CME Group, and market data platforms (as of July 8, 2026)
Additional context: EIA Today in Energy and STEO reports on inventories and global balances
This article is for informational purposes and reflects data available as of July 8, 2026. Markets move quickly—always verify the latest figures directly from EIA and other primary sources.