

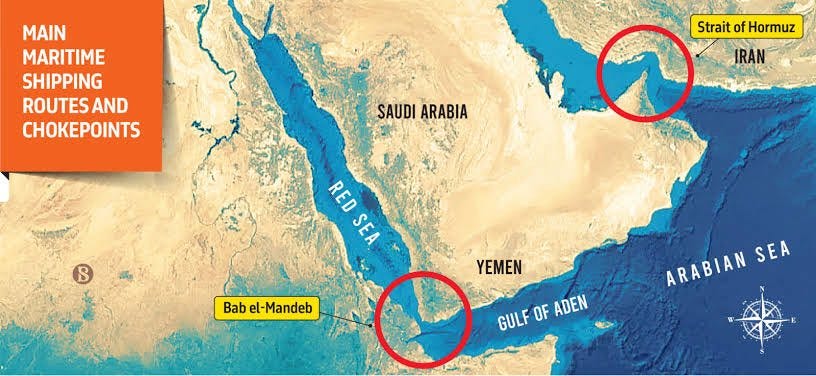
The February 2026 U.S.-Israeli strikes on Iran and Tehran’s retaliatory closure of the Strait of Hormuz marked more than a geopolitical flashpoint—they triggered the largest supply disruption in the history of global oil markets. Roughly 11–14 million barrels per day (b/d) of crude and condensate, plus a significant share of LNG, were effectively removed from circulation as tanker traffic through the world’s most critical chokepoint plummeted by 70% or more.
Brent crude surged past $100/bbl and at times approached $120/bbl; Asian LNG spot prices jumped 75% or higher.
Today we are seeing a drop to $88.10 for WTI, and I am not sure how long this will stay there, but for consumers, it is better than $140.
What began as a military confrontation has become a structural reset. Legacy reliance on the Strait of Hormuz—through which ~20% of global seaborne oil and LNG once flowed—has been exposed as untenable.
In their place, governments, producers, shipowners, and financiers are racing toward diversified supply chains: new bypass pipelines, expanded tanker fleets, aggressive upstream investment outside the Gulf, and aggressive replenishment of strategic reserves. The Iran conflict is proving to be the single biggest catalyst for capital deployment in exploration and production (E&P), midstream infrastructure, and maritime logistics in decades.
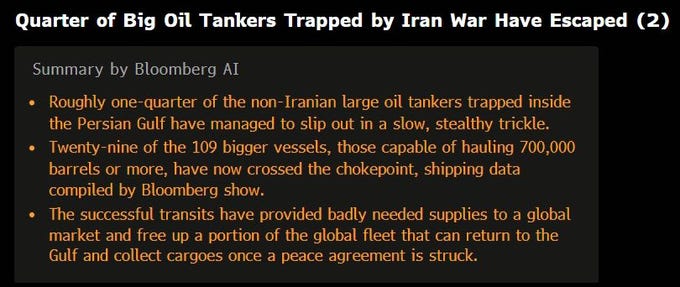
We are seeing some tankers slip through the Strait of Hormuz; 9 LNG Qatar tankers have made it through, and about 29 of the 109 large tankers have made it through the Strait of Hormuz, giving the market a much-needed injection.
But it also tells me that we really don’t know how the markets can rely on Supply and Demand numbers. The only number is the physical price at the time of delivery. That number will be the price at some point in the future.
June 24th is the next big contract date, and we will be watching. The paper price of oil always catches up with the physical price of oil at some point. Either physical coming down to meet paper, or paper moving up to catch physical delivery prices.
Big Banks Double Down on Energy Security Financing
Major banks have not stepped back from hydrocarbons; they have accelerated commitments. The latest Banking on Climate Chaos report shows the world’s 65 largest banks poured $906 billion into fossil fuels in 2025 alone, with JPMorgan Chase, Bank of America, and Japanese megabanks leading the pack.
Financing for oil-and-gas expansion (including pipelines and LNG terminals) rose 27% year-over-year to $508 billion despite net-zero rhetoric. Post-Hormuz, analysts expect this trend to intensify as banks back projects that reduce chokepoint risk. Private credit funds and infrastructure investors are already circling midstream assets, with deals such as Blackstone’s stake in EQT’s midstream portfolio and KKR’s ADNOC Gas Pipeline investment illustrating the appetite for resilient infrastructure.
Wall Street’s message is clear: energy security now commands a premium. Lending to E&P and tanker operators is no longer viewed as climate risk—it is viewed as geopolitical insurance.
Drilling Programs Ramp Up Worldwide
Pre-crisis 2026 forecasts called for flat-to-modest global E&P capex around $415–568 billion.
The Hormuz shock changed the math. Higher prices and visible supply fragility have unlocked budgets that were previously restrained by capital discipline. U.S. and Canadian operators—already the most responsive supply source—are signaling accelerated drilling in the Permian, Haynesville, and Montney. International majors are dusting off deepwater and LNG-tied projects in the Americas, Africa, and Asia-Pacific.
The windfall profits accruing to non-Gulf producers (ExxonMobil, Shell, Chevron, and national oil companies outside OPEC+) are being recycled into new wells and long-cycle developments.
Industry insiders describe the shift as “supply-led investment discipline.” With Gulf output curtailed for months and recovery uncertain even after any reopening, non-OPEC+ barrels are suddenly indispensable. The Iran war has turned theoretical energy-security rhetoric into immediate drilling rigs and frac fleets.
Tanker Orderbook Surges as Rerouting Becomes the New Normal
Even before the crisis, the tanker orderbook was historically elevated at ~16% of the existing fleet, with VLCC ordering tripling in 2024 and continuing strongly through 2025.
The Hormuz disruption has supercharged demand. Longer voyages around Africa or via alternative routes require more vessels to move the same volume. Freight rates for crude tankers exploded—VLCC earnings at one point quintupled—creating windfall cash flows that owners are plowing back into newbuildings.
Global shipbuilding data for early 2026 already showed tanker orders accounting for 32% of total new contracting, the highest share in years.
With the crisis now four months old and partial reopenings still fragile, owners and financiers are accelerating orders for VLCCs, Suezmaxes, and product tankers. The orderbook-to-fleet ratio is expected to climb further as operators hedge against future chokepoint volatility.
Every extra day at sea for Gulf cargoes effectively increases the required global tanker fleet by several percentage points.
Pipelines Bypass Legacy Chokepoints
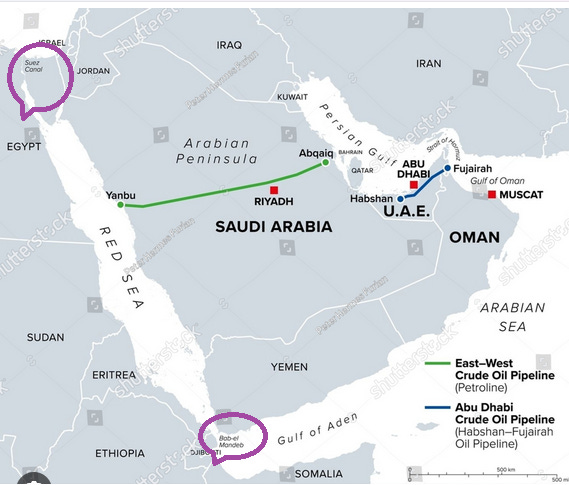
Gulf producers are moving fastest. The UAE has fast-tracked its West-East Pipeline project; construction is now 50% complete and slated to double export capacity through Fujairah (outside Hormuz) by 2027.
Saudi Arabia’s East-West pipeline is running at full 7 million b/d capacity to the Red Sea.
Broader concepts such as the U.S.-backed “ARAM Express” network envision overland corridors linking the Gulf to the Mediterranean, Red Sea, and Arabian Sea, reducing single-point failure risk.
These projects are no longer optional infrastructure—they are strategic insurance policies being executed at emergency speed.
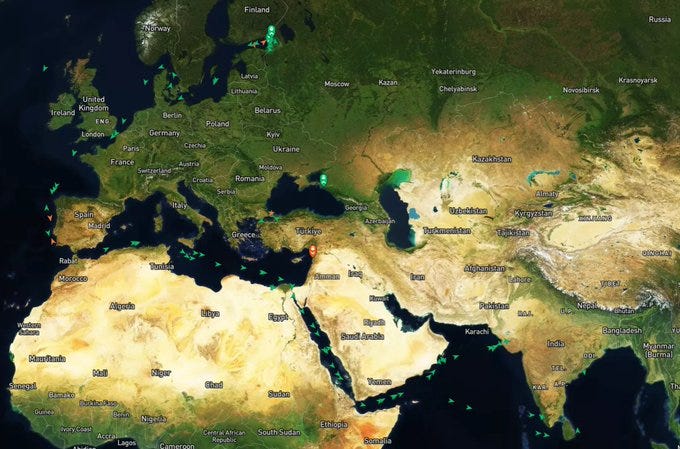
The image below shows tankers filling up at the Saudi Arabia East-West pipeline in the Red Sea and not going through the Strait of Hormuz. India is not out of the woods yet, as the Houthis have threatened in the last week to close the Bab el-Mandeb strait again, proving my point about this article.
Governments Prioritize Energy Security Over Reliance
The crisis forced the largest coordinated SPR release in history: 400 million barrels globally, including 172 million from the U.S. reserve.
Yet the same governments are now planning aggressive replenishment. The Trump administration has signaled intent to refill the U.S. SPR to near-capacity, with Secretary of Energy Chris Wright outlining purchases and exchange structures designed to return more oil than was released. For every barrel sold, 1.25 needs to be returned. This is a great thing as it keeps it out of the budgeting cycle.
China, India, Japan, and South Korea—already heavy users of Gulf supply—are accelerating diversification, domestic storage builds, and long-term contracts outside the Strait. Europe is revisiting LNG import infrastructure and demand-side measures.
The lesson is unambiguous: reliance on any single chokepoint is no longer an acceptable policy. Strategic reserves will be rebuilt, pipelines will be built, and domestic or allied production will be favored—even at higher cost.
Longer-Term Price Support and Investment Tailwinds
Rerouting alone adds millions of ton-miles to tanker demand, tightening the fleet and supporting higher freight rates. Reserve replenishment creates structural buying that offsets any near-term production recovery. Supply-chain rebuilding—new wells, pipelines, and ships—requires sustained capital that only elevated prices can justify. Analysts warn that even a partial reopening will not immediately restore pre-crisis flows; damaged infrastructure, insurance premiums, and lingering risk will keep effective supply constrained for quarters, if not years.
The Iran war has therefore done what years of net-zero rhetoric could not: it has made energy security investable. Capital is flowing to E&P outside the Gulf, to bypass pipelines, to tanker newbuildings, and to reserve infrastructure. Legacy chokepoints are being engineered out of the system. The result is a more resilient—but structurally more expensive—global oil and LNG market for the foreseeable future.
The Crude Truth is simple: Hormuz didn’t just spike prices. It rewired the map of energy investment for the next decade.
I, for one, am thrilled to be doing what we can as a private family-owned oil and gas company providing low-cost energy to the United States market.
If you have any questions, please connect with me on LinkedIn: https://www.linkedin.com/in/reytrevinoiii/
Also, Pecos Operating Website: https://pecosoperating.com/