

California’s leaders are doubling down on their ambitious climate agenda. In September 2025, Governor Gavin Newsom signed AB 1207 and SB 840, extending the state’s landmark Cap-and-Trade program—now rebranded as “Cap-and-Invest”—through 2045. The California Air Resources Board (CARB) followed up in May 2026 with program updates designed to keep the state on track for its 2030 and 2045 climate targets while touting “affordability for Californians, managing costs, and supporting jobs.”
Newsom hailed the move as “doubling down on our best tool to combat…climate pollution” and ensuring polluters pay for community projects. CARB’s own announcements emphasize long-term emissions reductions, carbon neutrality by 2045, and revenue for clean energy investments. On paper, it sounds like visionary leadership: a market-based system that caps greenhouse gases, generates billions for green projects, and positions California as a global climate leader.
But is California dreaming?
While the rhetoric focuses on a decarbonized future, the on-the-ground reality—driven by CARB’s stringent regulations, the Low Carbon Fuel Standard (LCFS), Net Zero mandates, and the original Cap-and-Trade costs—tells a different story. Independent reporting from Energy News Beat and data from the U.S. Energy Information Administration (EIA) and California Energy Commission (CEC) paint a picture of soaring energy costs, shuttered refineries, and skyrocketing reliance on imported fuels. The very policies meant to save the planet are forcing California to import more oil, gasoline, diesel, and jet fuel from abroad while Californians pay billions more at the pump.
The Government’s Promise vs. the Energy Reality
Official statements frame the Cap-and-Invest extension as a balanced win: it aligns with SB 32 and AB 1279 targets, provides market certainty, and funds affordability measures. CARB’s 2026 updates explicitly address “near-term economic concerns” while locking in post-2030 allowance budgets for 2045 net-zero goals.
Critics and data, however, show the cumulative impact of these layered policies—CARB’s ultra-stringent fuel specs, LCFS credits, Cap-and-Trade allowance costs, and refinery permitting hurdles—has accelerated refinery closures and production declines. Energy News Beat has repeatedly documented how these rules have turned California into an “energy island” isolated from the rest of the U.S. market, with boutique fuel requirements that limit supply options and drive up compliance costs.
Result? California now has just 7 operating refineries (down significantly from decades past), with major closures like Phillips 66’s Wilmington facility and Valero’s Benicia plant removing roughly 17% of refining capacity in a short period. In-state crude production continues to fall, forcing refineries to import 60-75% of their crude feedstock.
And 6 of the 7 remaining refineries are slated to close. The real crisis, or rub, for consumers is that they are at 100% of import capacity with the current 7 refineries. The pipelines and storage at the import facilities cannot be expanded, and they have limited import capacity.
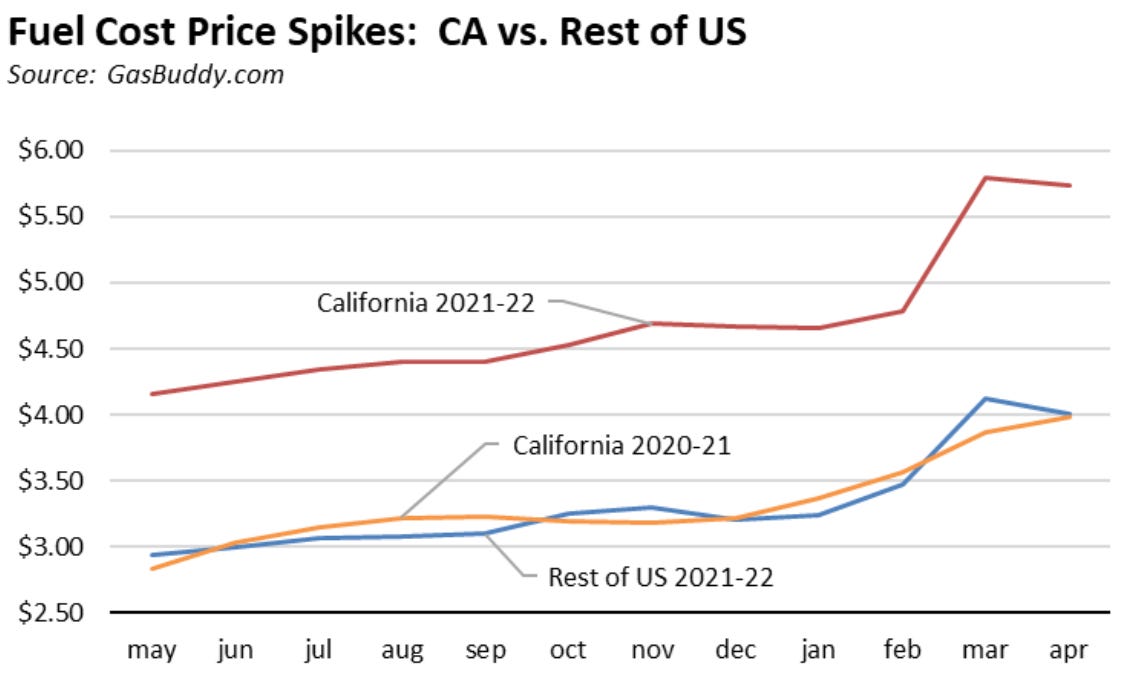
Charts: The Cost and Import RealityCalifornia’s gasoline prices have long carried a premium over the national average, but the gap has widened dramatically under these policies. Taxes, environmental fees, Cap-and-Trade/LCFS costs, and the state’s unique reformulated gasoline blend now add well over a dollar per gallon compared to the U.S. average. In 2025 alone, Californians paid an estimated $20 billion more for gasoline than if they had paid the national average.
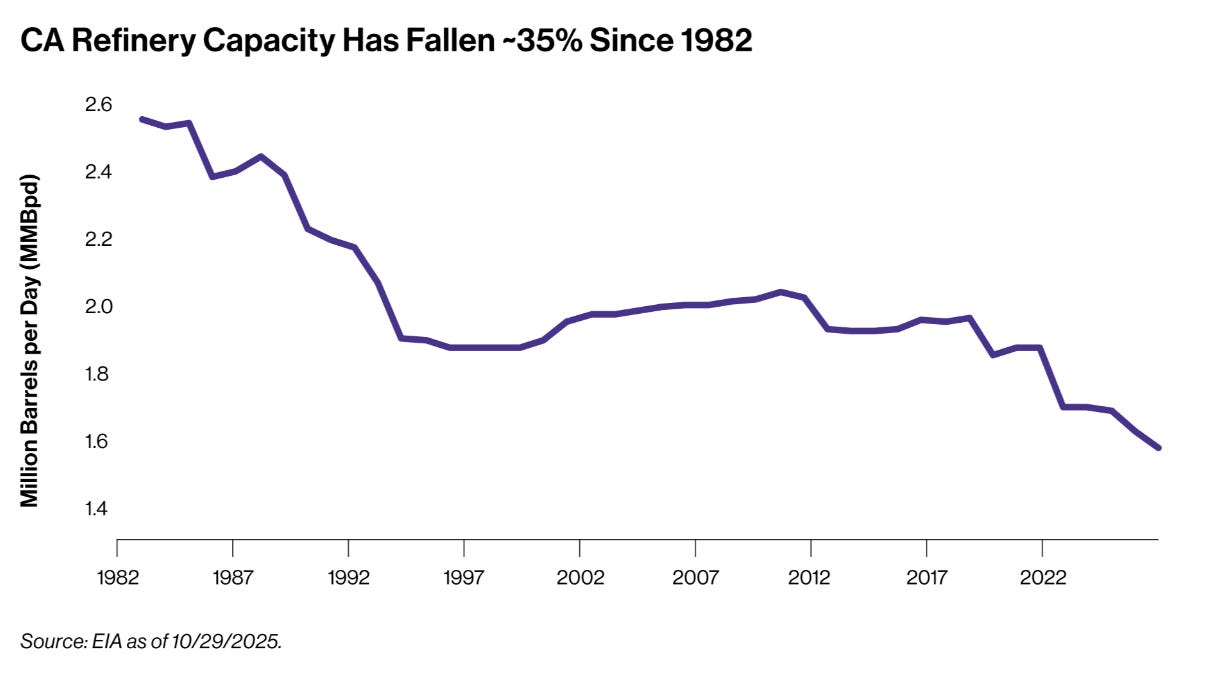
Refinery capacity has plummeted ~35% since 1982, with recent closures accelerating the trend and pushing product imports higher.
Import Surge Due to Policies
Post-closure data shows clear spikes:Gasoline imports to the West Coast (heavily California-driven) hit record levels—averaging ~119,000 barrels per day (bpd) in early 2025, up sharply year-over-year, with sources including Asia, the Bahamas, and rerouted Gulf Coast shipments via Jones Act workarounds.
Crude oil: Refineries import 60-75% of supply, much of it foreign.
Diesel and jet fuel: Imports rising as in-state fossil diesel production shifts and refinery output prioritizes other products; California now sources ~20% of jet fuel from abroad (e.g., India, South Korea).
These imports aren’t cheap or reliable—they expose California to global supply shocks, higher transportation costs, and national security risks, as Energy News Beat has warned. One analysis noted California refineries “maxing out” on jet fuel and diesel production while slashing gasoline output to chase regulatory credits.
Broader Market and Energy Implications
Extending Cap-and-Invest through 2045 locks in these dynamics for another two decades. Implications ripple far beyond the pump:
Consumer and Business Costs: Higher fuel prices feed into everything—groceries, trucking, manufacturing, and electricity (California’s commercial/residential rates have also escalated sharply). The “mystery surcharge” and regulatory add-ons mean Californians subsidize the system while competing states enjoy cheaper energy.
Energy Market Distortions: Refineries operate under constant regulatory uncertainty. Closures reduce domestic supply, increase import dependence, and raise the risk of shortages and price spikes during maintenance or disruptions. The state’s isolated “fuel island” status (limited pipelines, strict specs) amplifies volatility.
Overall Economy: Lost refining jobs, declining in-state oil production, and billions in extra energy costs act as a drag on growth. Energy News Beat frames it as a self-inflicted national security risk—importing more fossil fuels from Asia while claiming climate victory.
Net Zero Irony: Despite aggressive decarbonization, California’s policies have increased reliance on foreign refined products whose upstream emissions occur elsewhere. Global CO₂ impact is negligible, but local economic pain is very real.
As one Energy News Beat piece put it: “When you follow bad energy policies, bad things happen.” California is emulating European-style carbon taxes and Net Zero mandates—with similar results: spiking diesel and gasoline prices, refinery exits, and import dependence.
Appendix: Sources and LinksGovernment/CARB Statements
Governor Newsom on Cap-and-Invest updates: https://www.gov.ca.gov/2026/05/29/governor-newsom-applauds-updates-to-californias-cap-and-invest-program/
ICAP on 2025 extension: https://icapcarbonaction.com/en/news/california-extends-cap-and-trade-2045-renames-program-cap-and-invest
CARB program page and 2026 proposals: https://ww2.arb.ca.gov/our-work/programs/cap-and-invest-program
Energy News Beat Coverage (Negative Impacts)
US Gasoline Prices vs. Europe/California: https://energynewsbeat.co/energy-realities/us-gasoline-prices-lower-than-europe-california-says-hold-my-beer/
California’s Energy Crisis & Refineries: https://energynewsbeat.co/crude-oil/californias-energy-crisis-why-oil-refineries-are-still-essential/
Jones Act & Imports: https://energynewsbeat.co/crude-oil/the-jones-act-waiver-has-turned-into-a-boon-for-california-at-our-nations-expense/
Refineries maxing jet fuel/gasoline: https://energynewsbeat.co/jet-fuel/california-refineries-max-out-jet-fuel-slashing-gasoline-production/
Imports data: http://energynewsbeat.co/imports/how-much-diesel-gasoline-jet-fuel-and-other-oil-products-are-actually-imported-to-california/
Data & Charts Sources
EIA & CEC gasoline price breakdowns: https://www.energy.ca.gov/estimated-gasoline-price-breakdown-and-margins
API on CA price premium: https://www.api.org/energy-insights/charts-analysis/californias-gasoline-price-premium
American Energy Alliance on $20B extra cost: https://www.americanenergyalliance.org/2026/03/governor-gavin-newsoms-hypocrisy-on-gas-prices-is-breathtaking/
Refinery closures & imports: https://www.instituteforenergyresearch.org/international-issues/refinery-closures-increase-californias-reliance-on-fuel-imports/
EIA petroleum data: https://www.eia.gov/petroleum/data.php
The Crude Truth is clear: California’s extension of Net Zero and CARB initiatives may sound like a dream for the climate, but the energy market and everyday Californians are living a very expensive nightmare. Higher costs, more imports, fewer refineries—exactly the opposite of energy independence. Keep it crude, folks. Sources current as of June 2026. All data drawn from publicly available government and independent reports cited above.
Connect with me on LinkedIn: https://www.linkedin.com/in/reytrevinoiii/
Also, Pecos Operating Website: https://pecosoperating.com/
Regarding the statement: "Newsom hailed the move as “doubling down on our best tool to combat…climate pollution” and ensuring polluters pay",
Newsom is oblivious to the fact that the population of California is only 0.5% of the 8 billion living on this planet !
Newsom continues to incentivize foreign countries with significantly less environmental regulations to provide transportation fuels demanded by the 4th largest economy in the world.
The increase in worldwide emissions from those foreign based refineries, and the emissions from the merchant ships to bring those transportation fuels to California ports are of no concern to Newsom as he only breathes the air within the borders of California ONLY !
California is a dumpster fire. You can’t decarbonize life - life is dependent on carbon. You can’t virtue signal away your carbon consumption by laying off the hard work to produce refined hydrocarbon products to others and then trade credits for your consumption of their products. The net zero concept boils down to zero life.