

As of early August 2026, the global oil market remains trapped in a cycle of geopolitical shocks, fragile ceasefires, and structural underinvestment.
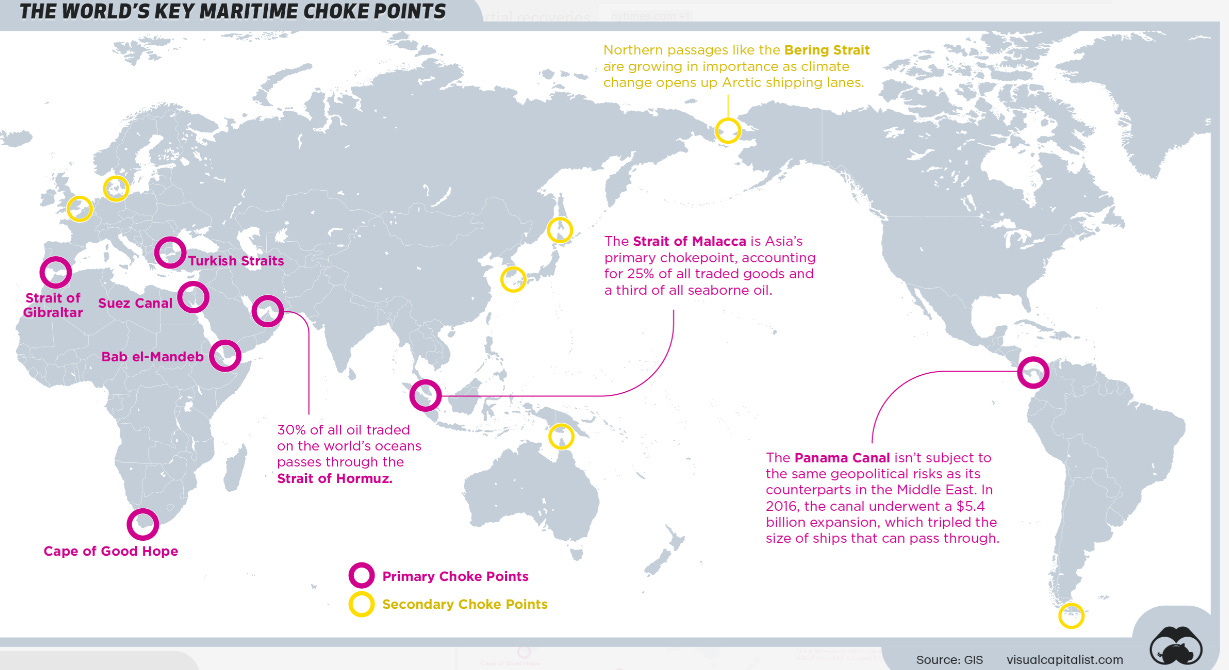
What began as a major disruption from the U.S.-Iran conflict in late February—effectively closing or severely restricting the Strait of Hormuz—has expanded to include Houthi threats and attacks affecting the Bab el-Mandeb Strait and Red Sea routes.
Prices have swung wildly, inventories have been drawn down, and physical logistics costs have soared. The question is no longer just about today’s barrel price, but whether the industry’s chronic capital discipline and reliance on vulnerable chokepoints will leave markets tighter for longer—or tip into surplus if flows normalize.
The Current State of the Global Oil Market
The market has endured one of the largest supply disruptions in modern history. Middle East Gulf production and exports dropped sharply after February 28, 2026, with estimates of peak outages exceeding 11–14 million barrels per day (mb/d) at times. Global supply is projected to contract significantly in 2026—IEA and OIES figures point to declines on the order of 3.7–4.5 mb/d for the year—before a potential rebound of 6–8 mb/d in 2027 if flows recover.
Demand has also weakened under the pressure of higher prices and disrupted product availability. IEA assessments have pointed to a possible annual demand contraction of around 1 mb/d in 2026 (the first since the COVID period in some forecasts), with growth rebounding toward 1.9–2 mb/d in 2027 under normalization. Inventories have been drawn heavily; OECD stocks reached multi-decade lows in places before partial recovery in June, and strategic reserves have been tapped. The balance remains tight in the near term, with deficits projected for much of 2026, shifting toward surplus in 2027 if Middle East output returns.
Volatility has been extreme: Brent surged above $100–$120+ at peaks in spring, collapsed toward pre-conflict levels near $70 in early July amid ceasefire hopes, then rebounded on renewed hostilities and Red Sea escalation. As of August 7, 2026, WTI was trading in the mid-to-high $70s and Brent in the low $80s.
Short of Exploration Dollars: The Capex Reality
Analysts have long warned of underinvestment in exploration and longer-cycle projects. Capital spending on exploration has lagged production growth for years. McKinsey has highlighted a “discovery gap,” with exploration capital expenditure declining roughly 6% annually since the 2014–15 price crash after earlier robust growth; discovered resources fell more than 50% over the last decade while production continued. Success rates have plateaued, and capital has shifted toward short-cycle shale and tiebacks.
S&P Global and others note that upstream spending by majors remains well below pre-pandemic peaks and has been largely flat. Exploration spending has hovered near $10 billion annually in recent years—down from higher levels earlier.
Wood Mackenzie describes the industry as “cash rich but capital cautious”: even with a potential $495 billion upstream cash windfall in 2026 (at ~$90 Brent), budgets have stayed disciplined, with development spend on course for slight declines and prioritization of optimization over major new commitments. Reserve replacement has weakened, and some analyses project large future shortfalls (tens of millions of barrels of oil equivalent per day by the 2030s–2040s from current commercial portfolios alone) without stepped-up activity.
This capital discipline protects returns and balance sheets but raises the risk of tighter markets later if demand proves more resilient or if geopolitical constraints persist on existing supply.
Where Oil Prices Stand Now—and Geopolitical Drivers
Current prices in the low-to-mid $80s for Brent reflect a partial unwinding of the extreme risk premium, yet they remain elevated relative to early 2026 pre-conflict levels and incorporate ongoing uncertainty. Forecasts vary widely with assumptions about Hormuz and Red Sea normalization. Recent analyst and agency views have clustered around Brent averaging roughly $80–$90 for 2026 (with quarterly swings) and lower in 2027 (often $65–$80 range) under recovery scenarios, though upside risks to $100+ remain if disruptions deepen.
Geopolitics dominates.
The Strait of Hormuz (historically ~20% of global oil and significant LNG) has seen repeated effective closures or severe restrictions, U.S. blockades on Iranian ports, and attacks. Parallel Houthi actions have threatened Bab el-Mandeb and Red Sea traffic, complicating Saudi East-West pipeline workarounds that had partially offset Hormuz losses. Combined, these chokepoints put large volumes at risk and force rerouting. Prices remain highly sensitive to every diplomatic signal, tanker incident, or military development.
Physical Delivery Costs: Insurance, Extra Miles, and the Pump
The “physical” market is amplifying price pressure at the consumer level. War-risk insurance premiums for Hormuz transits have spiked dramatically—from pre-conflict levels around 0.25% of hull value to peaks of 7.5–10% (and earlier as high as 10%). For a large tanker, this can mean millions of dollars per transit ($3–8 million or more in elevated periods). Red Sea/Bab el-Mandeb premiums have also risen sharply after Houthi attacks (to 0.5–3%+ depending on ports and routes).
Rerouting around Africa via the Cape of Good Hope adds 10–14 days (or up to a month on some Asia-bound legs), thousands of extra nautical miles, and substantial costs. Analyses put incremental voyage expenses at roughly $2.5 million or more per tanker (higher fuel, time charter, Suez fees where used, demurrage, and opportunity costs from reduced fleet availability). Some estimates for specific diversions reach $4–5+ million. These costs cascade into higher delivered crude prices for refiners.
Refiners facing elevated feedstock costs, constrained product availability from disrupted Middle East runs, and higher logistics pass much of this through. U.S. retail gasoline has seen sharp rises (national averages moving well above $4/gallon at peaks), with every $10/barrel crude move historically translating to roughly 24 cents/gallon at the pump—compounded by refining margins and distribution. European diesel and petrol have also climbed significantly.
The combination of crude, insurance, and miles is a direct contributor to higher prices at the pump beyond the headline futures number.
Near-Term Outlook and 2027: Life Outside the Chokepoints?
In the near term (remainder of 2026), expect continued volatility. Markets will track every development on Hormuz flows, Iranian production, Houthi activity, and any further U.S.-Iran diplomacy or escalation. Inventory rebuilding will take time even if flows improve; deficits could persist into late 2026 under cautious recovery assumptions. Prices may settle in a wide $70–$100 band depending on progress.
Looking to 2027, most base-case forecasts assume substantial supply recovery and a shift toward surplus (or smaller deficits), supporting lower average prices in the $65–$80 range for Brent. Demand growth is expected to firm with lower prices and normalized trade. However, this hinges on durable de-escalation and operational recovery (demining, infrastructure repairs, vessel willingness).
If oil supply remains heavily constrained by chokepoints—or if the industry fails to accelerate development of resources outside these vulnerable corridors (U.S. shale, Brazil, Argentina, Guyana, Canada, and other non-Middle East sources)—the picture darkens. Prolonged dual-chokepoint disruption could keep 2026–2027 balances tighter, support higher prices (scenarios of $100+ averages have been discussed), delay inventory rebuilds, and amplify the consequences of the exploration/capex shortfall. Diversification of supply routes and sources (pipelines, alternative basins, strategic stock management) becomes critical energy security policy. Without it, the market’s resilience to the next shock will be lower, and the underinvestment bill may come due sooner.
Oil markets are in flux because the physical and geopolitical foundations have been stressed harder than at any time in decades, while the industry’s capital response remains measured.
The path forward depends on whether diplomacy restores the old routes—or whether producers, refiners, and policymakers accelerate the build-out of supply that does not live or die by a handful of narrow waterways.
The Crude Truth is that price is only the surface; the deeper currents of investment, insurance, and geography will shape the next chapter.
This will also be supported by more fiscal control and resolve to give more money back to investors, vaulting the oil, gas, and LNG markets to the top of the energy sectors. Huge pipeline and new spending on SPRs around the world will also add to demand to fill the missing 1.4 billion barrels from the market.
Energy security is now at the forefront of the global markets, and this is putting a real strain on countries that took energy security for granted in the past.
I have enjoyed taking a much-needed break with my family, and we still have our oil and gas being delivered. Keeping low-cost energy moving to the United States markets is great for our family and investors.
The United States would be in a different place if we did not have our great oil and gas exploration companies.
And That is The Crude Truth.
If you have any questions, please hit me up on LinkedIn: https://www.linkedin.com/in/reytrevinoiii/
Also, Pecos Operating Website: https://pecosoperating.com/
Appendix: Sources and Links
Oxford Institute for Energy Studies, OIES Oil Monthly – Issue 56 (July 2026): https://www.oxfordenergy.org/publications/oies-oil-monthly-issue-56/
U.S. Energy Information Administration, Short-Term Energy Outlook (various 2026 releases, including July): https://www.eia.gov/emeu/steo/pub/contents.html and related PDFs
IEA Oil Market Report (June/July 2026 summaries and related): https://www.iea.org/reports/oil-market-report-june-2026 and subsequent
Business Insider / market reports on supply recovery and forecasts (June 2026): https://www.businessinsider.com/crude-oil-prices-today-supply-demand-outlook-forecast-hormuz-exports-2026-6
TD Economics, “Oil Markets Have Bought Time, Not Insurance” (August 2026): https://economics.td.com/ca-oil-markets
McKinsey, “The discovery gap: What it means for oil and gas exploration” (April 2026): https://www.mckinsey.com/industries/oil-and-gas/our-insights/the-discovery-gap-what-it-means-for-oil-and-gas-exploration
S&P Global, “COMMODITIES 2026: Industry calls for more oil, but capex spending sees muted growth”: https://www.spglobal.com/energy/en/news-research/latest-news/crude-oil/123125-commodities-2026-industry-calls-for-more-oil-but-capex-spending-sees-muted-growth
Wood Mackenzie mid-year outlook and related (July 2026): https://www.woodmac.com/press-releases/wood-mackenzie-mid-year-outlook-oil-and-gas-industry-cash-rich-but-capital-cautious-as-nearly-half-a-trillion-dollar-windfall-fails-to-trigger-a-spending-surge/
Insurance Business / Marsh reporting on war-risk premiums (multiple 2026 articles): e.g., https://www.insurancebusinessmag.com/us/news/marine/report-warrisk-insurance-braces-for-prolonged-elevated-premiums-as-hormuz-ceasefire-buckles-580558.aspx and related
Reuters on Red Sea insurance surge and diversion costs (July 2026): https://www.reuters.com/world/middle-east/war-risk-insurance-costs-surge-southern-red-sea-voyages-after-houthi-attacks-2026-07-23/ and https://www.reuters.com/business/energy/add-month-sea-25-million-what-it-costs-oil-tankers-flee-hormuz-bab-el-mandeb-2026-07-23/
AGBI analysis of multimillion-dollar shipping costs: https://www.agbi.com/analysis/shipping/2026/07/hormuz-and-red-sea-the-double-hit-threat-to-shipping-costs/
Price data (GuruFocus, Markets Insider, Investing.com equivalents for Aug 7, 2026): various live market sources confirming WTI ~$76–78 and Brent ~$82–83 range
Additional geopolitical and forecast notes from Kpler, Brookings, Reuters, Goldman Sachs, Morgan Stanley, JPMorgan, UBS, BMI, and others cited in contemporaneous reporting (June–August 2026)
All figures and projections are subject to rapid revision given ongoing events. Data drawn from public reports as of early August 2026.