

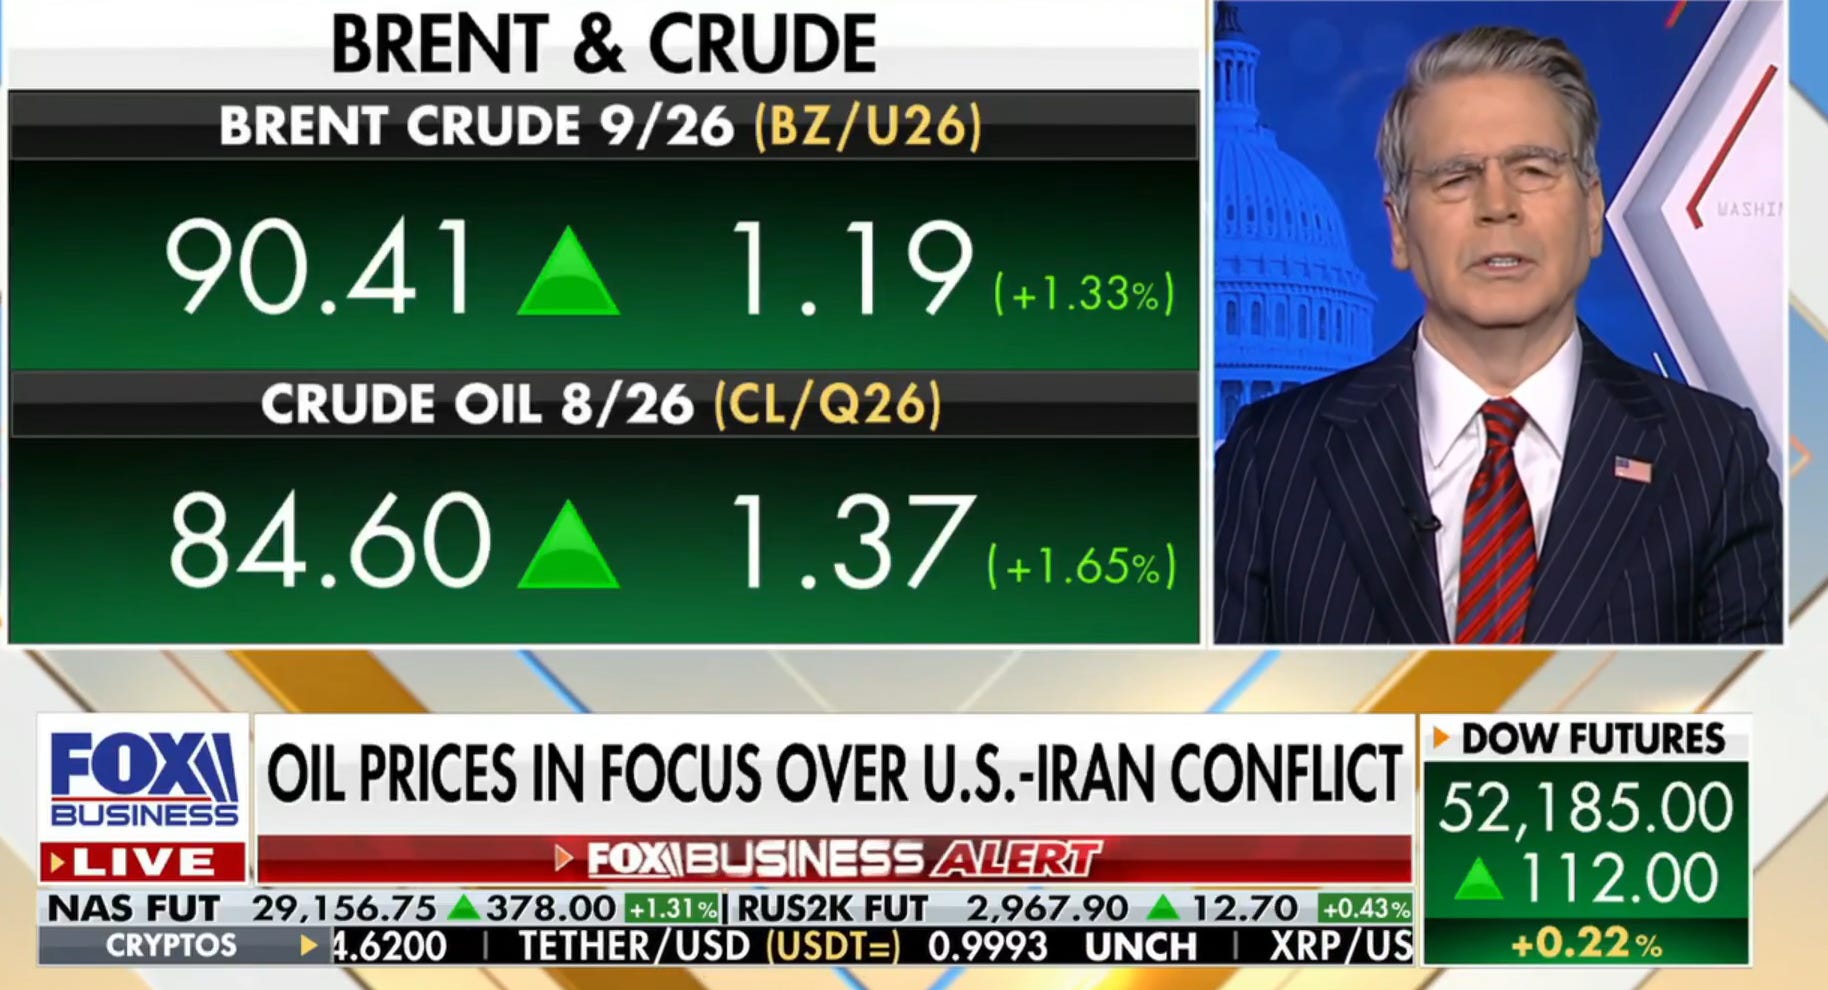
U.S. Treasury Secretary Scott Bessent delivered a blunt message on the Iranian regime’s financial underpinnings: authorities have identified “the money man for the Ayatollah,” are tracking properties and accounts worldwide, and have already frozen a crypto wallet linked to the Islamic Revolutionary Guard Corps (IRGC) worth $130 million.
Bessent highlighted the regime’s economic vulnerability, noting its currency is in freefall and inflation is reportedly around 180%. Treasury actions are intensifying pressure through sanctions on networks facilitating illicit oil shipments and weapons procurement, including high-profile targeting of figures like Mohammad Hossein Shamkhani and associated financiers.
Iran’s Oil Exports: Resilience, Collapse, and Partial Rebound (2024–2026)Despite years of U.S. sanctions, Iran sustained significant oil exports in 2024 and 2025, averaging roughly 1.48–1.55 million barrels per day (bpd), with the vast majority (often >99%) flowing to China via a sophisticated “shadow fleet” of tankers using ship-to-ship transfers, flag-hopping, and deceptive practices.
The February 2026 conflict triggered a sharp disruption. Exports plummeted amid a U.S. naval blockade and related enforcement:
May 2026 saw historic lows — as low as ~65,000 bpd (UANI data) or 209,000–260,000 bpd (Vortexa/Kpler estimates), the weakest levels since 2019–2020.
June 2026 brought a dramatic rebound after a U.S.-Iran Memorandum of Understanding (MoU) and temporary 60-day General License X (later revoked amid renewed attacks). UANI tracked 52.7 million barrels exported (~1.76 million bpd average), valued at ~$4.51 billion. Year-to-date 2026 through June: ~230 million barrels (~$19.4 billion).
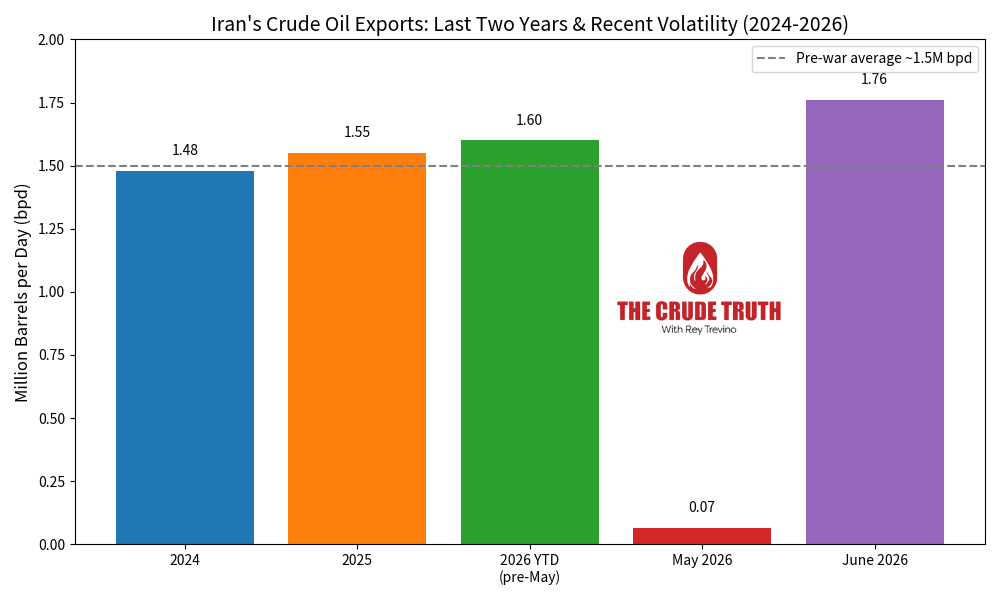
Key takeaway: Pre-war volumes were resilient thanks to China’s demand and evasion tactics. The 2026 war caused extreme volatility — near-total shutdown in May followed by a surge in June as previously stranded cargoes moved. Regime oil revenues remain critical but highly sensitive to enforcement and chokepoint risks.
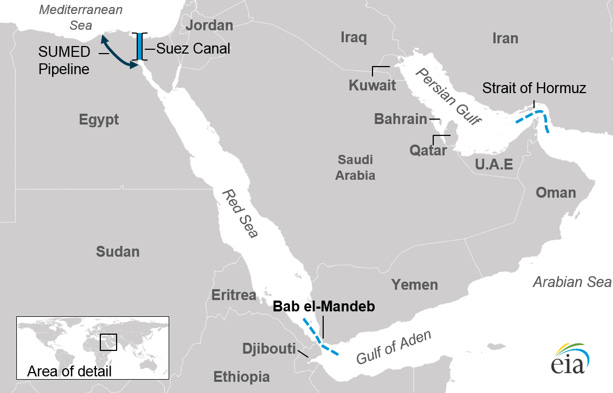
The Gulf Heats Up: Bab al-Mandeb Blockade and Houthi Escalation
While financial pressure mounts on Tehran, maritime tensions are escalating in the southern Red Sea. Iran-backed Houthis have declared a naval blockade targeting ships traveling to and from Saudi ports.
Recent developments include:
Multiple vessels (including at least three Chinese VLCCs) aborting transits through the Bab al-Mandeb Strait.
Two Saudi crude-carrying tankers reportedly making U-turns in the Red Sea and heading toward the Suez Canal instead.
Saudi Arabia had already rerouted a large portion of its exports (~90% via the Red Sea port of Yanbu and the East-West pipeline) to bypass the disrupted Strait of Hormuz. A sustained Houthi blockade on Bab al-Mandeb would close this critical alternative route for Asian-bound cargoes, creating simultaneous pressure on two of the world’s most vital oil chokepoints.
Analysts note that full disruption of both Hormuz and Bab al-Mandeb flows could trigger severe global supply shortages and sharp price spikes.
U.S. Inventories at Multi-Decade Lows: Fuel for Higher Prices Longer?
The U.S. Strategic Petroleum Reserve (SPR) has been drawn down aggressively to cushion earlier disruptions. As of mid-July 2026:
SPR stocks fell to ~311.4 million barrels — the lowest level since March 1983.
Total U.S. crude inventories (commercial + SPR) stood around 726 million barrels, near multi-decade lows.
Commercial stocks are also running below five-year averages after repeated draws. With SPR releases largely winding down, the market has far less buffer against new supply shocks.
What Analysts Are Saying
Market watchers see clear upside risks to oil prices from the combination of:
Renewed Hormuz disruptions and IRGC actions on shipping.
Houthi threats to Bab al-Mandeb and Saudi exports.
Depleted global and U.S. inventories.
Brent crude has already pushed above $90/bbl amid the latest escalation.
Some forecasts warn of $100–$120/bbl territory if both chokepoints face serious interference, with potential for “severe oil supply shortages” in the near term.
We do not see that spike holding for very long as demand destruction sets in. Oil looks to settle back to the $80 range in the long run.
The low-inventory environment amplifies any physical disruption — meaning even partial or temporary blockades could sustain higher prices for longer than in a well-stocked market. Normalization of Gulf flows (post any new ceasefire or deal) is viewed as uncertain and slow, with confidence in shipping routes remaining fragile.
Bottom Line
Treasury Secretary Bessent’s aggressive targeting of the Ayatollah’s financial networks coincides with fresh maritime escalation in the Bab al-Mandeb. Iran’s oil export machine has shown remarkable adaptability but remains vulnerable to enforcement and chokepoint pressure. Meanwhile, America’s depleted strategic reserves leave the market more exposed than at any point in decades.
The result: a volatile energy landscape where geopolitical risks are translating directly into sustained upward pressure on oil prices. Energy markets are watching both the financial “economic assassin mode” from Washington and the shipping lanes in the Gulf and Red Sea with heightened concern.
Check out LFS Chemistry, Sponsor of the Crude Truth, here: https://lfschemistry.com/
Follow Rey on his LinkedIn: https://www.linkedin.com/in/reytrevinoiii/
Also, Pecos Operating Website: https://pecosoperating.com
Appendix: Sources & Links X Posts Referenced
Eric Daugherty (@EricLDaugh):

Martin Kelly (@_MartinKelly_):


Mario Nawfal (@MarioNawfal):


Key Data & Reports
UANI June 2026 Iran Tanker Tracker: https://www.unitedagainstnucleariran.com/analysis/june-2026-iran-tanker-tracker
Reuters on May 2026 export lows: https://www.reuters.com/business/energy/iranian-oil-exports-fall-lowest-level-six-years-data-shows-2026-06-04/
EIA/IMF annual export averages (via FRED): https://fred.stlouisfed.org/series/IRNNXGOCMBD
U.S. SPR and inventory data (DOE/EIA reports, July 2026 coverage): Multiple outlets including Egypt Oil & Gas and Shafaq News summaries of official releases.
Analyst commentary on chokepoints and prices: Kpler, ING, Reuters, and market reports cited above.
Additional context drawn from Treasury Department releases on sanctions targeting Iranian networks (July 2026) and shipping intelligence on Red Sea/Hormuz flows. All data current as of July 21, 2026.
Lol. Wtf does that even mean? More nonsense from this clown administration.
*Is the strait open yet, Scott?*