

The comfortable narrative of plentiful, cheap oil has shattered. According to Jeff Currie, Chief Strategy Officer at The Carlyle Group and former head of commodities research at Goldman Sachs, the global oil market has moved beyond a mere supply deficit into a structural energy shortage. The buffers that masked underlying tightness—particularly massive Strategic Petroleum Reserve (SPR) releases—are nearly exhausted, and refined product markets are flashing urgent warning signals.
Currie’s Core Thesis: From Deficit to Shortage
In his analysis, Currie argues that the “illusion of abundance” was artificially sustained by coordinated inventory drawdowns across 32 IEA member countries, including the release of approximately 172 million barrels from the U.S. SPR. Global observed inventories crashed by over 250 million barrels between March and May 2026, with OECD government stocks falling to their lowest levels since December 1990.
The clearest evidence of shortage, Currie notes, isn’t in headline crude prices but in refined product markets. Crack spreads have surged to an unprecedented $70 per barrel—a historic level where the margin for refining nearly equals the price of the crude itself. This reflects a physical tightening in gasoline, diesel, and jet fuel availability.
Compounding factors include:
Damage to Russian refineries, wiping out over 1.4 million barrels per day of capacity (the lowest Russian crude processing since 2005) and prompting export bans on gasoline, diesel, and jet fuel.
Volatility in flows through the Strait of Hormuz amid geopolitical tensions.
The IEA warns that global oil inventories are on track for historical lows ahead of peak Northern Hemisphere summer demand.
Currie’s conclusion is stark: the market has transitioned into a structural energy shortage, with insufficient buffers to absorb further shocks.
US Rig Count: Resilient but Not Enough to Mask Tightness
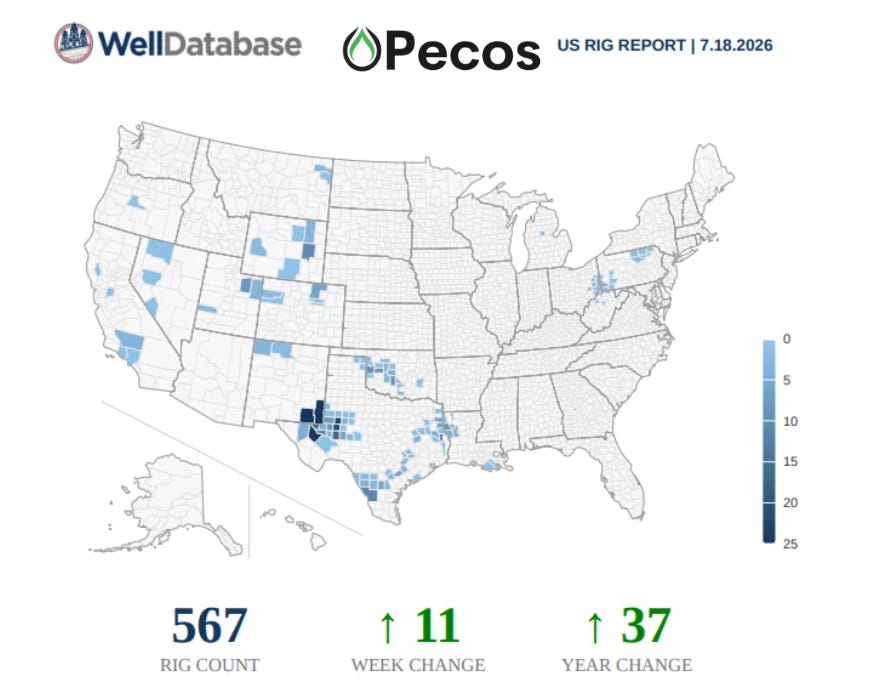
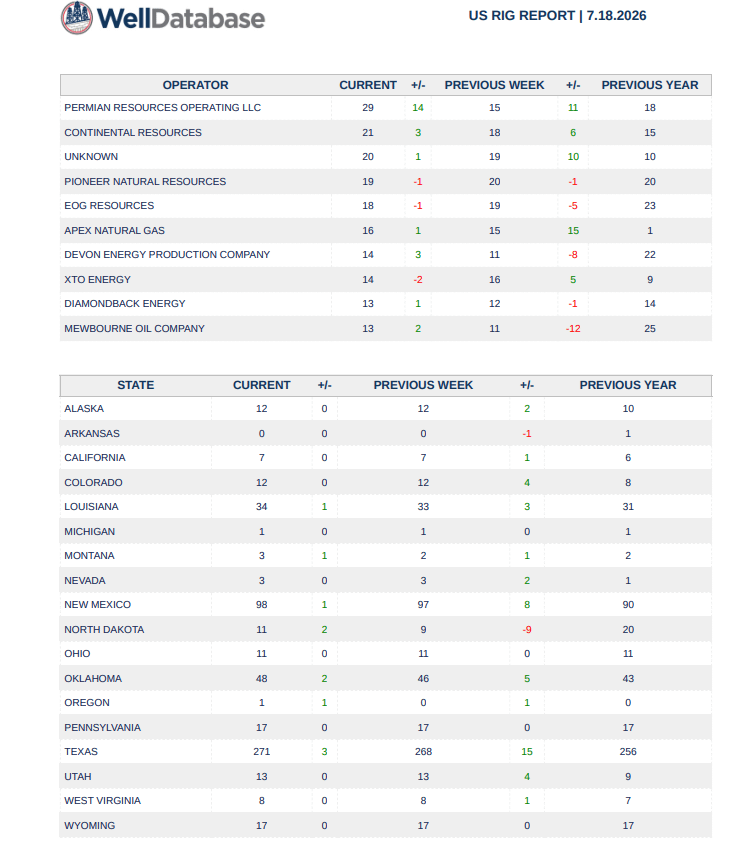
Recent data from WellDatabase’s July 18, 2026, weekly rig report shows the U.S. drilling rig count at 567—up 11 week-over-week and +37 year-over-year. Oil-directed rigs rose to 421 (up 7 WoW), while horizontal rigs (the efficient shale workhorse) stood at 496. The Permian Basin led with 261 rigs.
This resilience in U.S. shale activity—particularly in the Permian, Texas, and New Mexico—demonstrates that domestic producers are responding to price signals. However, the increase in rigs has not yet translated into inventory builds. Instead, it underscores that even with a growing U.S. supply, the market remains fundamentally tight due to global disruptions and strong underlying demand.SPR and Cushing:
The Buffers Are Nearly Gone
Cross-referencing with EIA data reveals the severity of the drawdown:
U.S. SPR levels have fallen dramatically. As of the week ending July 3, 2026, SPR stocks stood at approximately 319.5 million barrels, near multi-decade lows (down significantly from over 400 million barrels earlier in the year and on a path toward operational minimums).
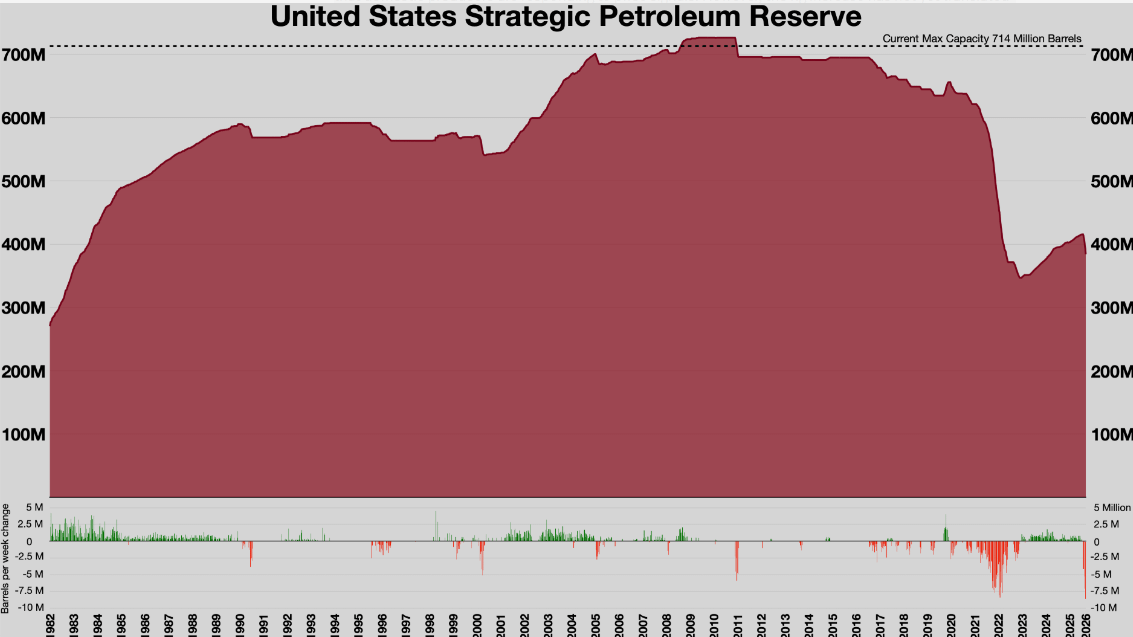
Long-term view of U.S. SPR levels showing the sharp recent decline.
Cushing, Oklahoma (the key WTI delivery hub) inventories are critically low. For the week ending July 3, 2026, Cushing crude stocks were 19.614 million barrels—near the ~20 million barrel operational minimum and at multi-year lows.
eia.gov
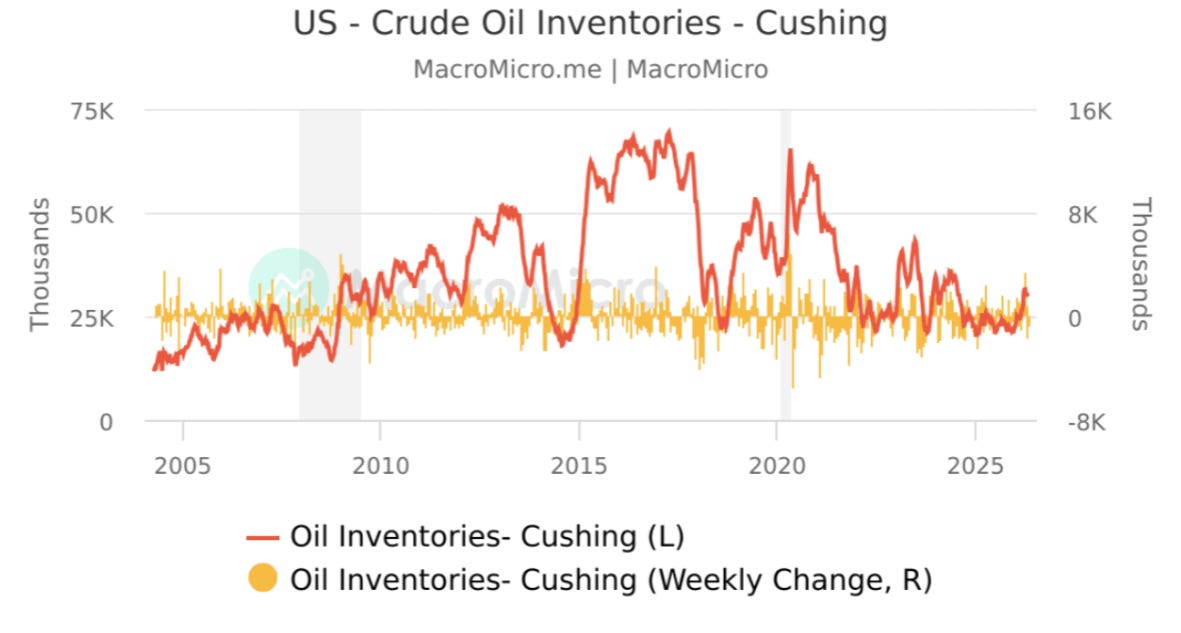
Historical Cushing, Oklahoma crude oil inventory chart highlighting the recent tightness near operational floors.
Commercial crude inventories (excluding SPR) have also drawn sharply in recent weeks, with total U.S. crude stocks (including SPR) at multi-decade lows. These levels leave little room for error as summer demand peaks.
What This Means for US Producers, Investors, and Consumers
US Producers
The combination of rising rig counts (especially horizontal drilling in the Permian) and persistently tight inventories is bullish. Higher realized prices and strong crack spreads support robust margins and free cash flow. Producers are incentivized to maintain or increase activity, though they must navigate potential volatility stemming from geopolitical developments or shifts in demand. The structural shortage narrative supports a constructive outlook for domestic output growth, particularly in efficient shale plays.
Investors
This environment favors energy equities, particularly upstream producers with low breakeven costs and strong balance sheets, as well as select midstream assets benefiting from tight logistics. Refiners may also see tailwinds from elevated crack spreads. However, the market remains sensitive to headlines around Hormuz flows, Russian refinery restarts, or policy responses. Long-term, the depletion of strategic buffers reduces the downside risk from oversupply and increases the potential for asymmetric upside in a true shortage scenario. Portfolio exposure to commodities or energy should be considered carefully, given the shift from “abundance illusion” to physical tightness.
Consumers
The pain is likely to show up first at the pump. Elevated crack spreads and product inventory pressures point to higher gasoline and diesel prices, even if crude benchmarks are somewhat moderated by remaining SPR releases or seasonal factors. Volatility could increase if further supply disruptions occur. The era of “cheap and plentiful” energy feels increasingly distant for American households and businesses reliant on transportation fuels.
Bottom Line
Jeff Currie’s warning is clear and data-backed: the illusion of oil abundance has been sustained by drawing down emergency stockpiles and ignoring refining bottlenecks. With U.S. rigs climbing but Cushing and SPR levels at precarious lows, the physical market is tightening. The summer driving and flying season will test these buffers further.
For the U.S. energy sector, this shift from surplus thinking to shortage reality is a game-changer—supportive for producers and investors positioned correctly, but a headwind for consumers facing higher fuel costs. The market is no longer pretending there’s plenty to go around.
Check out LFS Chemistry Sponsor of the Crude Truth here:
Follow Rey on his LinkedIn: https://www.linkedin.com/in/reytrevinoiii/
Also, Pecos Operating Website:
Appendix: Sources and Links
Primary Article: Jeff Currie: Illusion of Oil Abundance Is Gone – OilPrice.com
oilprice.com
Rig Report: WellDatabase Weekly Rig Report for July 18, 2026 – Energy News Beat
energynewsbeat.com
EIA Cushing Stocks: https://www.eia.gov/dnav/pet/pet_stoc_wstk_dcu_ycuok_w.htm (data as of week ending July 3, 2026)
EIA Weekly Petroleum Status Reports (various weeks in June–July 2026): https://www.eia.gov/petroleum/supply/weekly/
Carlyle “The Abundance Illusion” by Jeff Currie (June 2026): https://www.carlyle.com/carlyle-compass/the-abundance-illusion
Additional context from EIA inventory data and market analyses cross-referenced in June–July 2026 reports.
This article is written by the Crude Truth Substack and synthesizes publicly available data and analysis as of mid-July 2026. Oil markets are dynamic; always verify the latest EIA releases and market conditions.
Contact Rey on his LinkedIn above for the podcast or questions on the oil and gas markets.
The world holds approximately 1.77 trillion barrels of proven crude oil reserves.
At current global oil consumption rates of about 105 million barrels per day, primarily by the few wealthier developed countries, estimates suggest oil and natural gas could run out in less than 50 years, with coal having perhaps 70-100 years remaining.
• Oil reserves are approximately 1,770,000,000,000 barrels
• Oil consumption is currently 105,000,000 barrels/day
• Days remaining at current oil consumption 16,857 days
• Years remaining at current oil consumption rates in 46 years
Shockingly, 80% of the 8 billion on this planet, or more than 6 billion, are living on less than $10/day and have yet to join the industrial revolution!
• For the 6+ billion living in poverty on this planet, the worse form of air pollution is indoor air pollution, caused by poor people burning coal, wood, dung, candles, and paraffin in badly ventilated shacks, often without chimneys.
• Worldwide, more than 3 million people in poverty die prematurely each year from illnesses caused by indoor air pollution. These deaths are primarily linked to cooking with polluting fuels, resulting in respiratory infections, strokes, heart disease, and lung cancer.