

A storm is on the horizen, and it is called the “Crack Spread”. Refineries will be forced to choose between gasoline and diesel and optimize production based on demand.
Diesel is the workhorse of the physical economy. It moves grain, freight, construction equipment, and oilfield service rigs. When diesel is scarce, the shortage does not stay at the pump. It shows up in harvest costs, grocery inflation, freight rates, and well-site operating expenses. That is the situation the United States and the rest of the world are in now—not because crude oil has vanished, but because the system that turns crude into middle distillates has been broken at several chokepoints at once.
The crisis is global. The United States is better positioned than Europe or Asia, but it is not insulated. High U.S. refinery utilization and large product exports are what is keeping American shelves and tanks supplied. Those same exports are also why domestic distillate inventories remain uncomfortably low heading into harvest and heating season.
A product shortage, not a crude shortage
Doomberg writes in his August 23 essay, Marginal Rations, frames the problem cleanly: the world’s fleet of engines and the world’s refinery slates evolved around the molecular mix of a typical historical crude barrel. That match worked until wars and export bans overwhelmed the buffers. Diesel consumption in the United States has not surged this year. Availability has.
U.S. diesel crack spreads—the difference between ultra-low-sulfur diesel (ULSD) and WTI crude—printed an all-time high near $102 per barrel on August 17 and remained in triple digits the next day. That is four to six times a normal mid-cycle crack. Northwest Europe’s gasoil crack and Singapore’s gasoil crack have also been extreme. Crude benchmarks, by contrast, have eased from wartime peaks. WTI has recently traded in the low $80s. The market is telling operators something important: molecules of crude are available; barrels of diesel are not.
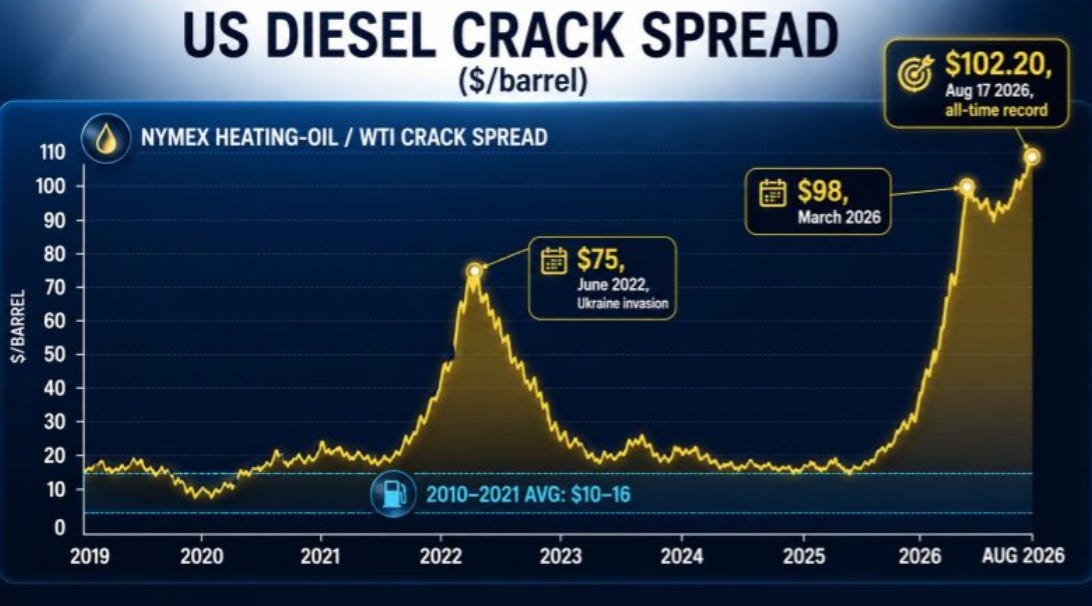
That divergence is the crack-spread story. When crude falls faster than diesel, the refining margin widens.
The reason is structural, not speculative:
Middle East and Russian diesel exports have been cut by more than half in some estimates—from roughly 3.3 million barrels per day to about 1.6 million. Ukrainian strikes on Russian refineries and Russia’s own export bans removed a major swing supplier. Disruption around the Strait of Hormuz constrained both crude and, more importantly, refined-product flows.
Asian refiners forced onto lighter replacement crudes produce less diesel per barrel. Diesel yield can drop from the high 50s–60% range toward 40% on a lighter slate.
Global refining throughput has run millions of barrels per day below year-ago levels. Goldman Sachs and the IEA have both described diesel as the epicenter of the product squeeze.
Crude can sometimes be rerouted around a chokepoint. Finished diesel cannot be conjured from a different molecule without a working hydrocracker, a clean product tanker, and a destination willing to take it.
How the market is being reshaped around chokepoints
Three maritime and industrial chokepoints now dominate product balances:
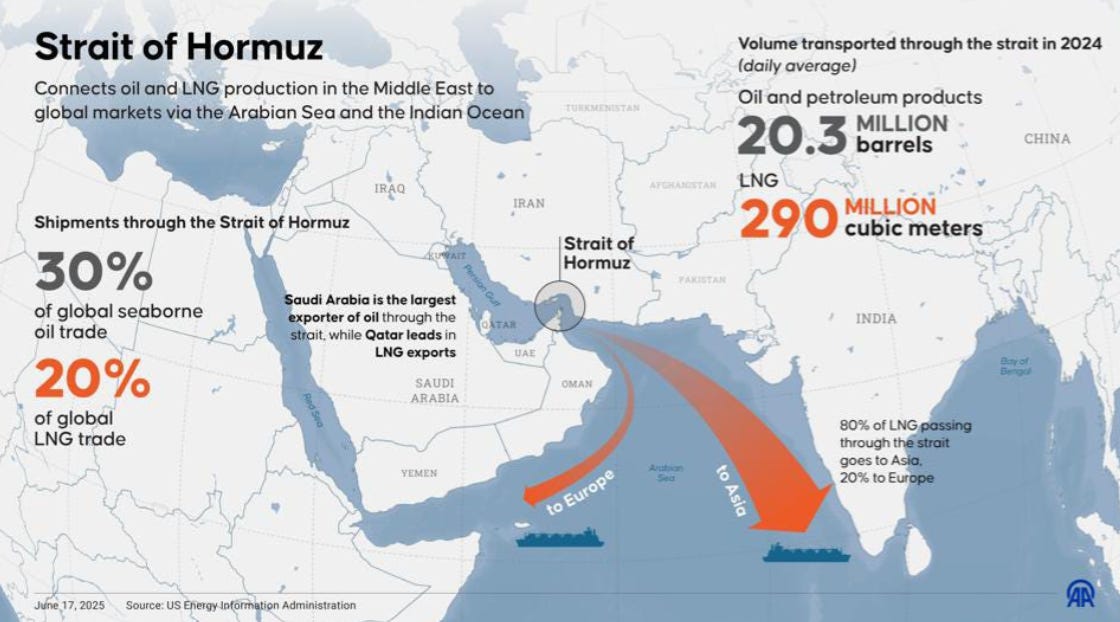
Strait of Hormuz — Historically about 20 million barrels per day of oil and products, including a large share of seaborne crude and a meaningful share of refined product. Even partial disruption or insurance-and-escort friction reduces the volume of medium-sour barrels that Asian complex refiners were built to crack into diesel.
Russian refining and Black Sea logistics — Drone damage plus export bans turned the world’s second-largest diesel exporter into a net constraint. Repairs are slow under sanctions.
Red Sea / Bab el-Mandeb and related routing — Longer voyages, higher freight, and delayed product cargoes tighten Atlantic Basin balances even when crude is available.
The United States sits on the other side of that map. Gulf Coast complex refineries can run domestic light tight oil and imported medium sours. Product tankers can leave Houston and Port Arthur for Europe and Latin America. That is how the U.S. consumer is being supplied: not by isolation, but by becoming the marginal product exporter to a world that has lost Russian and Middle Eastern diesel.
How the United States is keeping up with demand
U.S. refiners have been running near the top of the utilization range—recent weekly figures around 97%. Distillate production has been on the order of 5.1 million barrels per day. Four-week average distillate product supplied is about 3.8 million barrels per day, down roughly 2% year over year. Domestic demand is not the problem. Exports are the swing variable. Weekly distillate exports have recently run 1.6–1.9 million barrels per day, well above year-ago levels in several weeks. Those cargoes support Europe and other importers. They also keep U.S. inventories from rebuilding.
That is the policy and commercial bargain of 2026. The United States has spare complex refining capacity relative to war-damaged systems abroad. Using it keeps global freight and food systems from seizing. It also means American stocks do not get a comfortable cushion before winter.
Retail prices already reflect the tightness. EIA’s on-highway diesel average for the week of August 24 was $5.652 per gallon, up about 20 cents on the week and more than $1.90 versus a year earlier. California printed $7.04. Gulf Coast retail was $5.48—still expensive by any pre-war standard.
Current inventory levels
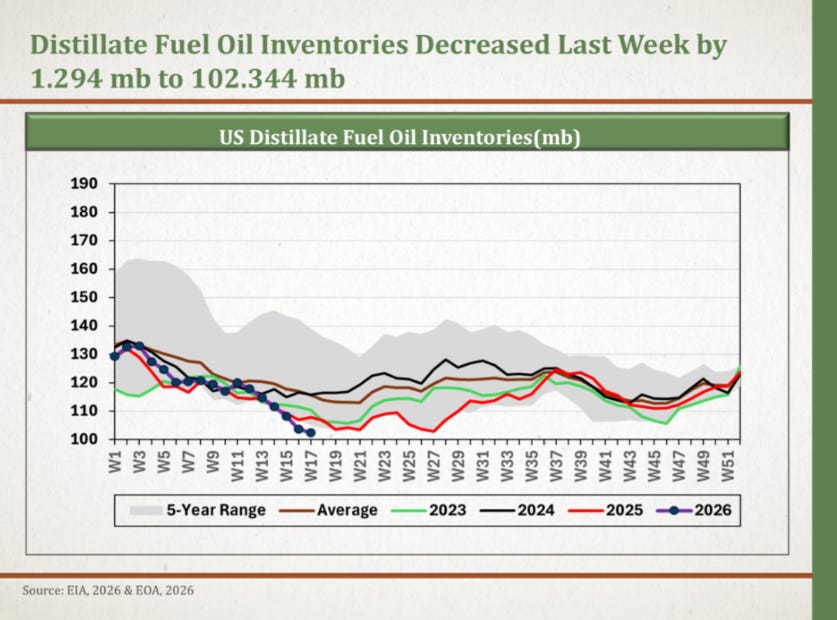
Official EIA weekly data through the week ending August 14 showed U.S. distillate stocks at 105.6 million barrels. The August 26 release covering the week ending August 21 showed another sizable distillate draw of about 2.2 million barrels, taking stocks to roughly 103.4 million barrels. Distillate inventories are now on the order of 14% below the five-year average for this time of year. Commercial crude, by contrast, is near or slightly above its five-year seasonal average at about 428.9 million barrels.
That split is the entire thesis in one table: crude is adequate; diesel is not.
Days of cover have been running near 30 days on some weekly snapshots—thin for a fuel with inelastic demand and a harvest still ahead. PADD-level volatility remains high on the East Coast, which depends on Gulf Coast and import flows.
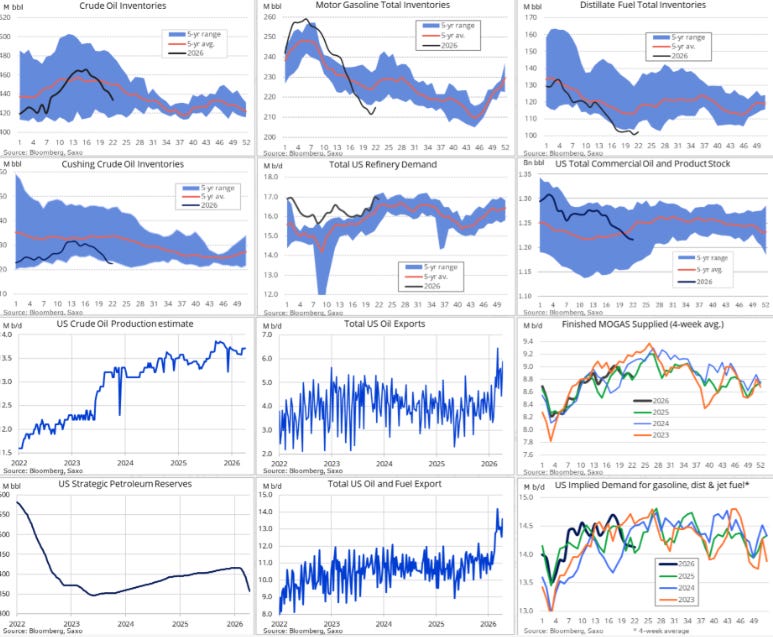
What Doomberg means by “marginal rations”: Marginal rations are not a prediction of empty tanks at every truck stop. It is a warning about the last increment. When inventories sit near operational minimums, the next lost cargo, the next refinery outage, or the next cold snap is priced at a very high marginal cost. Triple-digit cracks are that price signal. They ration diesel to the highest-value uses—and they tax everything else.
Doomberg’s point about historical crude slates matters for operators. U.S. shale is light and sweet. It is excellent for gasoline and, with enough conversion capacity, for diesel. It is not a perfect substitute for the medium-sour barrels that many overseas hydrocrackers were designed around. When those barrels and those plants are offline, the U.S. system can help—but only up to the limit of coking, hydrocracking, and product-tanker availability.
How investors and consumers should look at this
For investors and energy operators
High diesel cracks are a refiner and product-exporter story first. Complex Gulf Coast systems with conversion capacity capture the margin. Simple topping plants do not.
For E&P companies, including Permian operators, diesel is a cost line, not a revenue line. Service rigs, water hauling, sand, and crude trucking all run on diesel. Sustained $5.50–$7.00 retail diesel raises lease operating expenses and service-company bids even if WTI is not at $120.
Equities and credit that benefit: large independent refiners, product midstream, and tanker exposure. Risks: high-cost trucking-dependent producers, retailers with thin fuel margins, and any winter-heating region that still uses distillate.
Watch three numbers weekly: EIA distillate stocks versus the five-year band, ULSD–WTI crack, and U.S. distillate exports. A rebuild in stocks with cracks still elevated would be the healthy outcome. A further draw into September–October with cracks above $80 would mean the shortage is still deepening.
For consumers and the broader economy
Diesel is a freight tax. Food, building materials, and manufactured goods move on trucks. That tax is already in the CPI pipeline.
Demand destruction is messy. Farmers and truckers do not stop because diesel is $5.65. They pass the cost through or delay capital spending.
The United States is not facing European-style station queues as a base case. It is facing a high-price equilibrium in which the U.S. consumer subsidizes global product balances via exports and tight domestic stocks.
Heating-oil regions in the Northeast should treat the next 90 days as a planning window, not a waiting period.
Bottom line for Pecos Operating Company
The impending diesel crisis is real, global, and already visible in cracks, inventories, and pump prices. It is not a replay of a classic crude-oil shock. It is a refining-and-logistics shock centered on chokepoints and lost conversion capacity. The United States is meeting demand by running hard and exporting hard. That strategy works until stocks hit the operational floor or winter demand arrives.
Operators should budget for elevated diesel and service costs even if crude remains in the $70–$90 range. Investors should treat the diesel crack—not Brent—as the cleaner signal of physical tightness. Consumers should expect freight and food inflation to stay sticky until global product inventories rebuild, which requires either restored Russian and Middle East refining or a demand slump large enough to close the gap.
Neither of those is guaranteed before the heating season.
You have heard me on radio and TV interviews talking about the Crack Spreads and the fiscal responsibility of our great oil and gas operators, and it is paying off. If the refiners can’t provide good returns to their investors, they can’t afford the 10 to 100 million dollar annual maintenance updates to keep our 128 refineries in the US operating.
That is the Crude Truth.
Check out our Website: https://pecos.energy/
For investors and consumers, the storm is on the horizen!
The ignorance of the “energy ILLITERATE” leaders is shocking, as they NEVER explain how the “energy” from wind turbines and solar panels can provide TRANSPORTATION FUELS: jet fuel for military and commercial aircraft, diesel fuel for trucks and construction equipment, gasoline fuel for cars, bunker fuel for merchant and cruise ships, and the exotic fuels for the space programs !
Energy "REALITY" is that wind turbines and solar panels ONLY generate electricity but CANNOT make any products or transportation fuels for life as we know it.
Planes, ships, trucks, and cars run on transportation fuels manufactured FROM crude oil by multi-billion-dollar refineries.
There is NO case for unreliable electricity, as wind and solar CANNOT make any transportation fuels or products for the 8 billion on this planet.
The world has become dependent on the products and transportation fuels MADE FROM oil, the same products and transportation fuels that unreliable green electricity from Wind and Solar CANNOT make!