The tentative U.S.-Iran agreement to end months of conflict, reopen the Strait of Hormuz, and launch 60 days of further talks represents a meaningful de-escalation—but it is far from a comprehensive or guaranteed resolution. Oil markets are already reacting with relief (prices dropping sharply), yet underlying physical tightness, interpretive gaps between Washington and Tehran, and a critically depleted U.S. storage buffer mean volatility and risks remain high.
This is a complex, multi-layered situation. Here is a breakdown of the key developments as of mid-June 2026.JD Vance’s CBS Interview:
Optimism with Caveats
In a recent CBS interview (aired on CBS Sunday Morning and related segments), Vice President JD Vance struck an optimistic but measured tone. He described the U.S. as “very close” to a deal addressing Iran’s nuclear program “for the long term”—not just during the Trump presidency, but in a way that ensures “my kids can say when they’re adults, ‘Iran is not going to have a nuclear weapon.’”
Vance emphasized economic benefits for the U.S. and stressed enforcement mechanisms over blind trust in Tehran: “I don’t trust anybody… What I do trust is my own ability to negotiate [and] our administration’s ability to negotiate.” He indicated the deal could materialize “in the next week” or take “months,” but “we’re going to know a lot before the midterm elections.”
He also addressed the Strait of Hormuz reopening and pushed back on reports of massive asset releases to Iran, calling some coverage misleading. The full text of the agreement was slated for release this week.
Strait of Hormuz Reopening and the Signing Timeline
The core near-term win is the planned reopening of the Strait of Hormuz (through which ~20% of global oil and LNG once flowed). The tentative memorandum of understanding (MoU) includes lifting the U.S. naval blockade on Iranian ports and restoring shipping, with initial implementation expected shortly after formal signing—widely reported for later this week (around June 19–20 in Geneva or Europe).
Trump has framed it as authorizing a “toll-free” opening. However, the deal structures an initial period of freer passage within a broader 60-day ceasefire extension for deeper negotiations on nuclear issues, sanctions relief, and other matters. Full pre-war traffic levels are not expected overnight.
IRGC Tolls, “Services,” and the 60-Day Window
During the crisis, Iran’s Islamic Revolutionary Guard Corps (IRGC) effectively controlled traffic through a “toll booth” system, requiring documentation, escorts, and payments—sometimes reported up to $1–2 million per vessel (often in yuan or crypto). Iran framed these as “service fees” for navigation, security, or environmental protection rather than outright tolls.
Under the new deal, the initial phase appears toll-free (or with heavily restricted fees). However, Iranian statements and interpretations suggest that after the 60-day period, fees or a regulated system could return. One analysis noted the text allows for only 60 days of free passage before potential charges resume.
Trump has publicly insisted on “permanently toll-free” access.
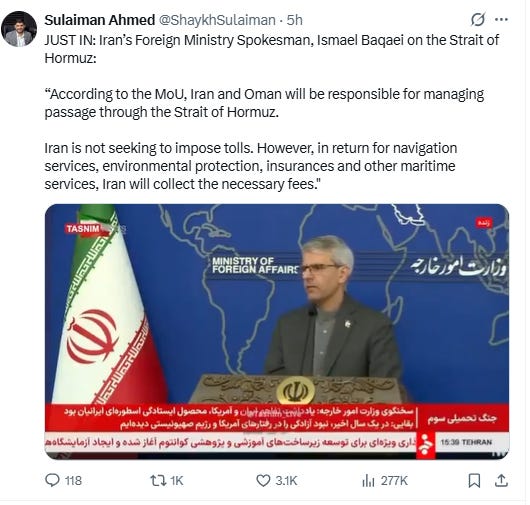
This is a clear point of friction.
Differing Visions: Trump Administration Terms vs. Iranian/IRGC Positions
Earlier Iranian proposals included a 14-point plan focused on ending hostilities, lifting sanctions/blockades, and sanctions relief. U.S. counter-proposals emphasized strong nuclear curbs, missile limits, and permanent free passage.
The current interim framework (sometimes referenced in reporting as elements of a 14-point agreement or MoU) prioritizes:
Immediate/near-term Hormuz reopening and blockade lift.
60-day window for nuclear talks (stockpiles, enrichment levels, IAEA oversight).
Gaps persist: The U.S. stresses verifiable, long-term nuclear prevention without major upfront cash transfers. Iran seeks economic relief and retains leverage over the strait. Israel’s separate actions (e.g., in Lebanon) add another layer of complexity. The deal is an interim step, not a final JCPOA-style accord.
Oil Market Realities: Prices, SPR, and Cushing’s Dangerous Lows
Oil prices have responded positively to news of de-escalation. As of June 15, 2026, Brent traded around $83.66/bbl and WTI near $80–81/bbl—down significantly (reports of 4–5%+ drops in sessions) from conflict peaks.
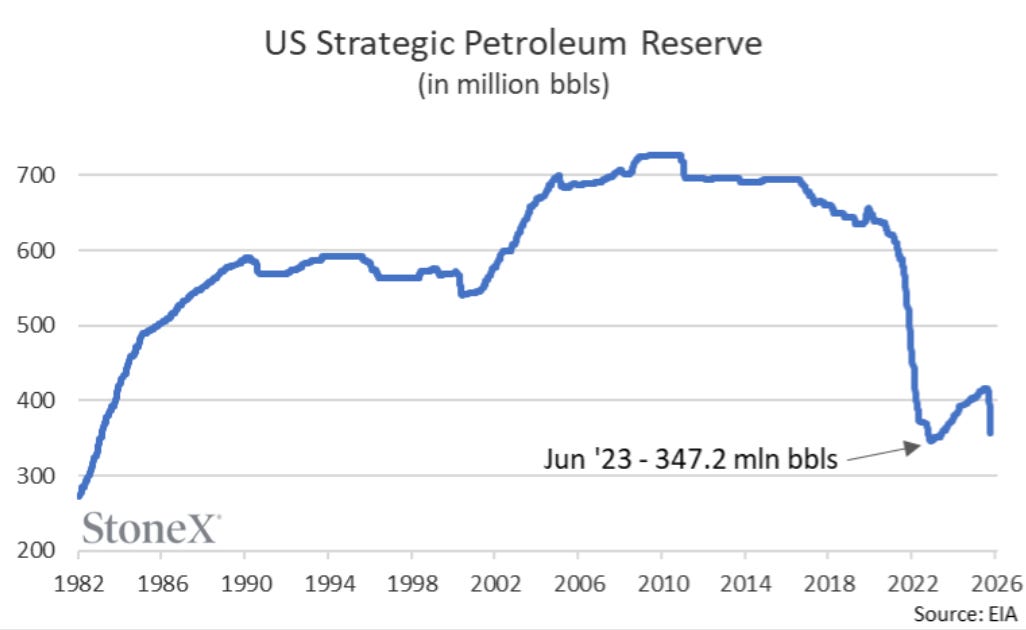
Strategic Petroleum Reserve (SPR): Heavily drawn down to support global supply amid Middle East disruptions. Levels stood at approximately 349 million barrels as of early June 2026—near multi-decade lows and approaching or below some Reagan-era figures. Weekly draws have been substantial.
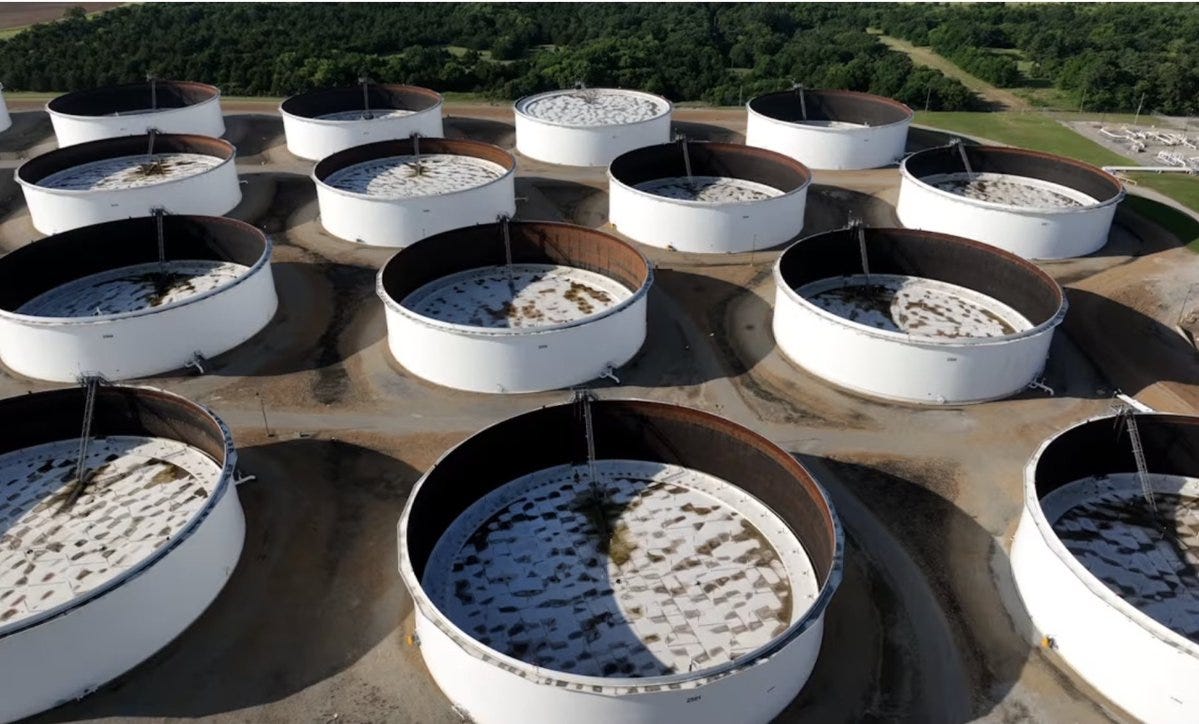
Cushing, Oklahoma (the key WTI delivery hub): Inventories have plummeted to critically low levels. As of June 5, 2026: 21.64 million barrels (down from normal ~40 million and working capacity of ~75–78 million).
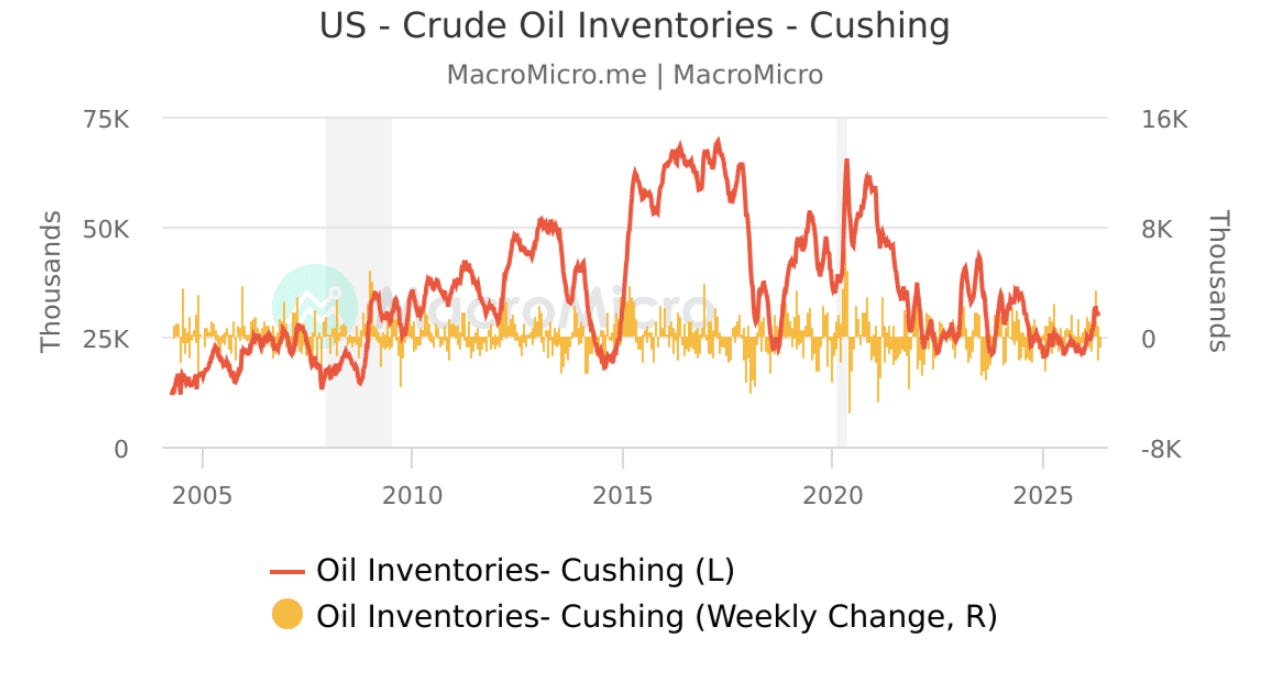
Cushing crude inventory charts showing the steep drawdown to near-operational bottoms.
Operational minimums are around 20 million barrels—below which pumping, blending, and pipeline transfers to Gulf Coast refineries become problematic. Analysts note Cushing could hit these levels within weeks (next EIA data around June 17). High U.S. exports have drained domestic stocks to plug the global supply gap.
2020 Negative Oil vs. Today’s Low-Storage Environment
In April 2020, WTI futures went deeply negative (around –$34 to –$37) primarily because Cushing storage was full. Traders couldn’t take physical delivery, creating extreme contango and forcing sellers to pay buyers to take the oil.
Today, the situation is inverted: storage is nearly empty. This creates risks of physical tightness, stronger backwardation (prompt prices higher than future months), and potential delivery squeezes or volatility around contract expirations. The June 2026 futures (and nearby contracts like July) face scrutiny as inventories approach minimum operational thresholds before meaningful new supply from the Gulf can fully ramp.
A spike in prompt contracts is possible if the deal’s implementation lags or if logistical bottlenecks emerge—even as longer-dated prices ease on expectations of eventual supply recovery.
Analyst Views on Rebalancing: 2026–2027 Timeline
EIA and other forecasters see a gradual process:
Short-term (June–July 2026): Prices may average higher (~$105/bbl Brent in some scenarios) while Hormuz traffic resumes incrementally and shut-in production restarts.
Inventories: OECD stocks headed toward multi-decade lows by year-end 2026 (potentially ~2.3 billion barrels, lowest since 2003 data begins). Days of supply could hit ~50 days.
Tanker fleet and balances: Crude tanker demand growth ~1–2% in 2026 (balanced with supply growth ~1.5–2%). Product tankers face more supply growth. Rebalancing is slowed by low starting inventories; full restoration of flows and stock builds likely extends into 2027.
Longer-term (2027): As supply normalizes, EIA projects Brent averaging ~$79/bbl. However, executives (e.g., from Exxon, Chevron) warn of lingering tightness and potential spikes to $140–160+ if reopening is slower than hoped.
Tanker availability and logistics will take time to normalize fully. The market remains structurally tight well into 2027 in many outlooks.
The Crude Truth Bottom Line
The U.S.-Iran deal is a positive development that should ease immediate supply fears and support lower prices in the near term. Yet differences over tolls post-60 days, the scope of nuclear commitments, enforcement, and Israel’s role introduce real uncertainty. Critically low U.S. inventories (SPR and especially Cushing) leave little buffer—meaning any implementation hiccup could trigger sharp price moves, particularly around upcoming futures expirations.
This is not the end of the rainbow. It is a fragile truce and the start of another phase of negotiations. Oil traders and consumers should monitor signing details, 60-day progress, inventory data, and actual tanker traffic through the Strait of Hormuz closely. The physical market’s tightness suggests caution rather than complacency.
The Crude Truth is much like the ugly baby on the doorstep that nobody wants to talk about. Have you ever gone to a family reunion and had your cousin bring in their new baby who looks more like a zoo animal than a human baby? We are in the ugly baby stage of negotiations, and it isn’t good.
The IRGC cannot be trusted, and they are already planning on putting out tolls, and every oil-producing country is planning to build pipelines around the Strait of Hormuz. The Iranians pulled their only Trump Card, and it will not hold the world hostage once the pipelines are added, or oil is drilled in more volume from other places in the world. All of this is moving at an accelerated pace.
Buckle up and stay tuned to the Crude Truth for some insights as we wade through the noise in the news.
Connect with me on LinkedIn: https://www.linkedin.com/in/reytrevinoiii/
Also, Pecos Operating Website: https://pecosoperating.com/