

The Strait of Hormuz remains the world’s most critical chokepoint for oil, with roughly 20% of global petroleum liquids transiting its waters under normal conditions. Disruptions here have once again dominated headlines in late June 2026 amid renewed U.S.-Iran tensions following an earlier conflict and interim ceasefire efforts. Oil prices have fluctuated sharply, inventories are tightening rapidly, and analysts like veteran strategist Jeff Currie are warning of prolonged physical market stress even as futures prices react to diplomatic headlines.
Jeff Currie’s Perspective: “Sell the Tweet, Buy the Molecule” Jeff Currie, executive co-chairman at Abaxx Markets (and formerly senior advisor/chief strategy officer roles at Carlyle and Goldman Sachs), has been vocal about the disconnect between paper markets and physical realities.
In mid-May 2026, Currie warned that Asian oil markets were at “tank bottoms,” with Europe not far behind and the U.S. potentially facing shortages by July due to curtailed flows through the Strait of Hormuz from the Iran-related conflict. He noted that shrinking global inventories were strengthening Iran’s negotiating leverage.
By June 16, 2026, on Bloomberg Television, Currie stated that even with a ceasefire holding, Hormuz flows “may not normalize until the end of the year.” He emphasized that restoring normal shipping and production would take months, not days or weeks. Currie has repeatedly highlighted that paper (futures) markets have disconnected from physical markets — a theme he described earlier in the conflict as the “mirror image of Covid,” where “you can’t print molecules.” His advice: “Sell the tweet [deal headlines], buy the molecule [physical tightness].”
Currie sees inventories continuing to drop as a key bullish factor for physical prices in the longer term, despite short-term futures volatility tied to ceasefires and diplomacy.
Recent Strikes and Escalation in the Strait of Hormuz
Tensions escalated sharply in late June despite mid-June ceasefire/de-escalation efforts (including a reported interim U.S.-Iran memorandum). On or around June 25, a Singapore-flagged cargo ship (M/V Ever Lovely) was struck by an Iranian drone while exiting the Strait along the Omani coast.
On June 27, a tanker (reported as the Panama-flagged VLCC KIKU, laden with Qatar Energy crude) was hit by an unidentified projectile in the Strait, damaging its bridge (no pollution or crew injuries reported).
The UK Maritime Trade Operations (UKMTO) raised the threat level in the Strait to “substantial.” The Joint Maritime Information Center also elevated alerts.
The U.S. responded with strikes on Iranian missile and drone storage locations, as well as coastal radar sites near the Strait (including areas like Qeshm Island). CENTCOM described these as a “powerful response” to the attacks on commercial vessels. Iran traded strikes, including reports of attacks on U.S.-linked targets or bases.
This marks the worst escalation since the interim peace deal. Earlier in June, ships had begun moving via a safer southern “highway” route in Omani waters, but the latest incidents have paused some UN evacuation efforts and heightened war-risk insurance and caution for tankers.
U.S. Response and Broader Context
The U.S. has conducted targeted, limited strikes aimed at degrading Iranian capabilities threatening maritime traffic while avoiding full-scale escalation. President Trump has publicly condemned the attacks as violations of the ceasefire. The situation remains fluid, with ongoing diplomatic efforts alongside military signaling.
Analysts note that full normalization of Hormuz traffic could still take significant time even under a stable ceasefire, as mines, damaged infrastructure, and insurance issues linger.
Cushing Inventory Levels: Approaching Operational Floor
U.S. commercial crude inventories at the key WTI delivery hub in Cushing, Oklahoma, have fallen sharply:
Week ending June 5, 2026: 21.64 million barrels
Week ending June 12: 20.03 million barrels
Week ending June 19: 18.96 million barrels (down another ~1.08 million barrels). This is way below Operational Minimums, and we are checking the rumors that Cushing has been bypassed, and oil is flowing in from the Canadian Oil Sands straight to the Gulf refineries. We will keep you posted if this is confirmed.
These are the lowest levels since 2014 and are now at or below the widely cited operational warning/floor of around 20 million barrels (Kpler and Wood Mackenzie analyses). Below this threshold, operational challenges arise due to “gunk”/sludge at tank bottoms, making it difficult to meet delivery demands without stress.
Draws have been driven by strong refining demand, exports, and global supply gaps from Hormuz disruptions. Further declines could exacerbate local tightness at Cushing.
SPR Levels and Operational Minimum Timeline
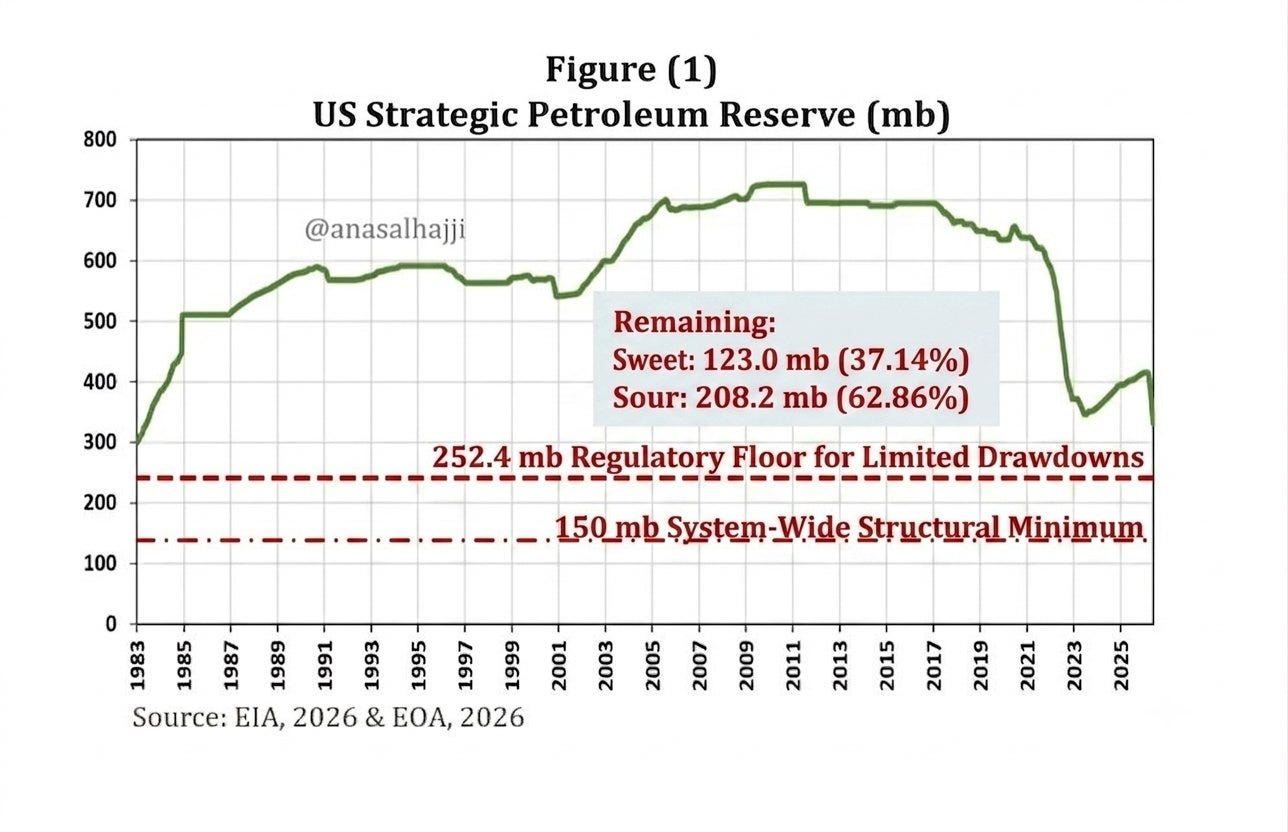
The U.S. Strategic Petroleum Reserve (SPR) has seen aggressive drawdowns amid the conflict:
As of June 19, 2026: Approximately 331.2 million barrels (continuing a steep decline from ~372 million in late May and lower levels since the conflict began).
This is among the lowest levels since the early 1980s. Large weekly releases (sometimes exceeding 8–9 million barrels) have been used to offset supply shortfalls.
Operational minimum considerations:
A SecDef-certified policy floor exists around 243 million barrels tied to prior release authorizations.
Some analyses reference a broader “operationally low” or legally referenced threshold near 150 million barrels.
Physical/unrecoverable floors are estimated much lower (tens of millions), but policy and practical limits kick in earlier due to cavern constraints and national security needs.
At recent accelerated draw rates (around 1.4+ million barrels per day in peak weeks), projections from mid-May data pointed to the 243 million barrel certified floor being approached or crossed around mid-August 2026. With June levels already at ~331 million and ongoing draws, critical operational discussions or constraints could intensify in August or sooner if releases continue at the pace. Further drawdowns would require additional certifications and face increasing scrutiny.
WTI Futures Price vs. Physical Delivery Price
As of late June 2026, front-month or near-term WTI crude futures have traded in the $69–$71 per barrel range (e.g., August contract around $69.23–$70.24 recently, with volatility tied to deal news).
WTI futures serve as the benchmark for physical delivery at Cushing. However, in tight physical markets like the current one:
Physical/spot crude has often traded at a premium to futures (reports earlier in the conflict showed physical prices significantly higher, sometimes $20–$35+ or more above paper markets in extreme tightness). Current ballpark for physical delivery is $107.43.
I am seeing some people claim that oil may hit glut status soon at $50. That is possible if the demand destruction of the global financial crisis has already kicked in, but $50 will not get new wells drilled in the United States.
Make no mistake, there are two reasons we have not had oil sustained above $100 a barrel: China’s use of its SPR and its reduction in diesel and downstream production. Couple that with the United States drawing down its SPR at record levels and hitting all-time export levels.
Futures can reflect expectations of future normalization (leading to backwardation in the curve), while immediate physical delivery faces real-world constraints from low inventories, logistics, and geopolitics.
Currie and others have noted this disconnect between paper and physical markets.
Investors should monitor the Cushing basis/differential and the shape of the futures curve (contango vs. backwardation) for signals of physical tightness.
What Should Investors and Consumers Watch?
I recommend following Dr. Anas Alhajji; he points out that we are heading toward a brick wall at the end of August or September, as the SPR is heading toward operational minimums, with Cushing already poised.
For investors:
Weekly EIA inventory reports (Cushing and total commercial stocks) — further draws below operational floors are bullish for prices.
SPR draw rates and any policy announcements on releases or refills.
Hormuz shipping data, insurance rates, and tanker traffic volumes.
Geopolitical headlines vs. actual physical flows (Currie’s “sell the tweet” lens).
Energy equities, but with caution on volatility; physical tightness supports longer-term upside per analysts like Currie.
Broader demand signals (global economy, summer fuel use) and OPEC+ responses.
For consumers:
Gasoline and diesel pump prices — these lag crude but will reflect sustained high benchmarks and any local shortages.
Potential for elevated fuel costs through summer and into fall if Hormuz issues persist.
Watch regional impacts: Asia and Europe feel physical shortages first; the U.S. has buffers via SPR and domestic production, but not indefinitely.
Bottom line: While futures prices have pulled back on ceasefire hopes, physical market fundamentals — low Cushing stocks, rapid SPR depletion, and uncertain Hormuz normalization — point to ongoing tightness. Jeff Currie’s warnings underscore that resolving the molecule flow takes time. Markets remain highly sensitive to any further escalation or credible de-escalation in the Strait.
The biggest reason consumers are protected is due to the fiscal responsibility of the United States Exploration and production companies.
On a Side Note:
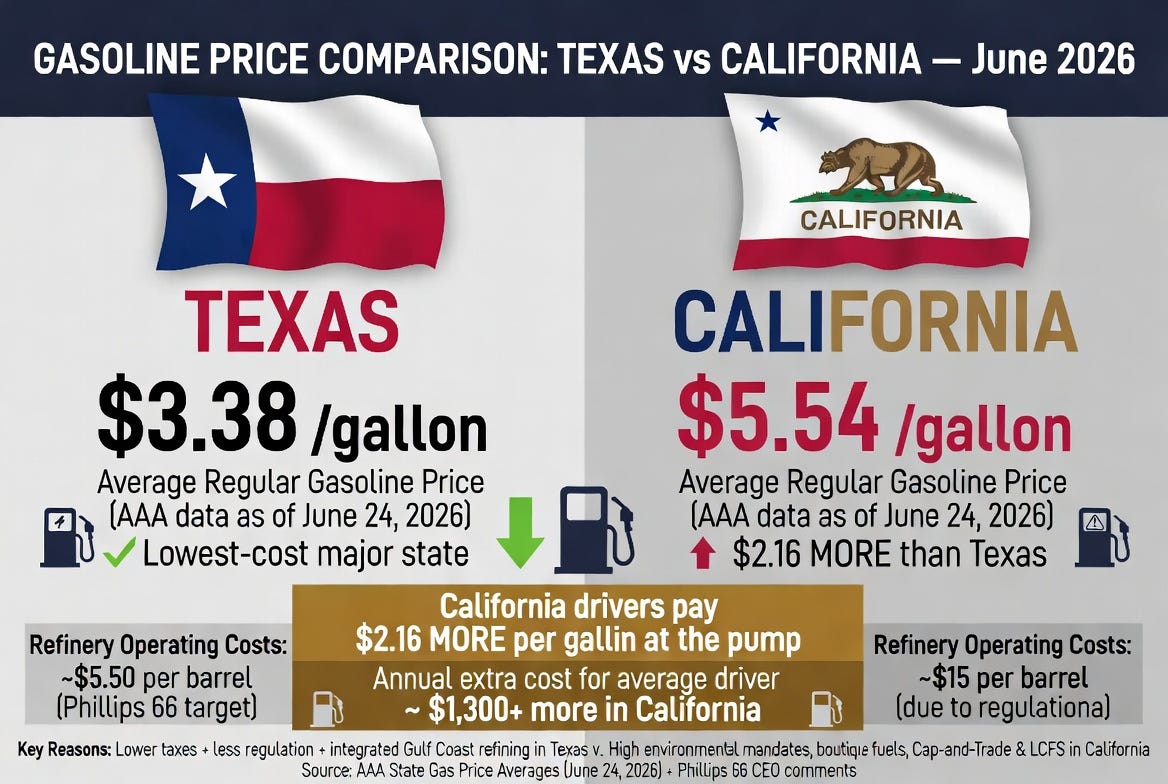
Watch the refinery accusations of price gouging. There is some hanky-panky going on in California, using a tool that several gas stations may be using to potentially coordinate pricing among competing gas stations. This is completely different from the accusations against President Trump, as gas prices are not coming down as fast as oil prices. Just look at the difference between paper and physical delivery to see the lag time.
Check out the single biggest issue with high gas prices: the Government. In Texas, the cost to produce a barrel of oil is $5, and in California, it is $15. Oh, and they have to import 40% to 60% of their diesel, jet fuel, and gasoline from Asia, adding to their costs. Then they have an estimated $1.70 in taxes and fees per gallon that other states don’t pay.
So when President Trump gets his investigation, I hope they check the state governments. Just saying, and you will see Blue States are higher than Red States.
If you need to ask a question or get on the Crude Truth podcast, reach out to me on LinkedIn.
Looking forward to our great 250th Celebration of the United States.
Appendix: Sources and LinksJeff Currie Comments:
CNBC (May 25, 2026): Oil market at ‘tank bottoms’ in Asia... https://www.cnbc.com/2026/05/25/oil-prices-iran-war-carlyle-currie.html
Bloomberg (June 16, 2026): Jeff Currie Says Hormuz Flows May Not Normalize Until End of the Year (video/article) https://www.bloomberg.com/news/videos/2026-06-16/currie-hormuz-flows-may-not-normalize-until-year-s-end-video
Additional context from Energy Aspects and other interviews.
Hormuz Incidents & US Response (June 2026):
Reuters, AP, CNN, Fox News, Telegraph, GCaptain reports on tanker/cargo ship strikes (June 25–27).
CENTCOM statements on U.S. strikes.
UKMTO threat level updates.
Inventories:
EIA Cushing data: https://www.eia.gov/dnav/pet/hist/LeafHandler.ashx?n=PET&s=W_EPC0_SAX_YCUOK_MBBL&f=W (June 5/12/19, 2026 values).
EIA Weekly Petroleum Status Report (June 24, 2026 release).
SPR levels via EIA/Trading Economics/YCharts (June 19: ~331.2 million barrels).
Energy.gov SPR Quick Facts (May 28 data context): https://www.energy.gov/hgeo/opr/spr-quick-facts
Analyses: Wood Mackenzie, Kpler, Reuters on operational floors.
Prices:
CME Group, CNBC, Oilprice.com, Yahoo Finance for WTI futures (~$69–71 range late June).
Historical context on physical premiums from market reports.
General Context:
Multiple Reuters, Bloomberg, CNN, AP articles on escalation and ceasefire dynamics (June 2026).
EIA Short-Term Energy Outlook references on global inventories.
All information is based on publicly available reports as of June 28, 2026. Markets move quickly — always verify latest EIA releases and credible news sources for real-time updates.
Cushing can go to ~17m barrels. And SPR is irrelevant, was 4.4mb per day, now down to maybe 0.7mb, so not really a factor anymore.